Saturday, April 16, 2022

Barron's Round Up

Some interesting stuff in Barron's this weekend.

Christine Benz sat for an interview and although I disagree with her on target date funds (my take is to run screaming from the room, waving your arms frantically to get away from them), she had a great comment about paying off your mortgage early, she called it a peace-of-mind allocation. For years, I've been saying that just looking at the numbers and nothing else, you probably shouldn't pay it off early but for some people, and I am one, there is huge emotional value paying down and then off the mortgage. We're almost 10 years in to a 15 year mortgage and our balance is down to $5074. It will be paid off this summer.

Hopefully we have many more years here, healthy and able bodied enough to do what needs to be done to stay here. For now, all signs point to that working out. Props to Benz for articulating this point so succinctly. 

One of the Trader columns looked at whether for 2022, investors should sell in May and go away as the cliché goes. "While the Fed tightens, investors should use seasonality to their advantage and be spectators to the drama this summer" the article said. It came early in the article and it's not out of context. That is insanely bad advice and indeed, it was walked back later in the article.

For a little history, the article noted that when the S&P 500 is down for the first four months of the year, it has gone on to fall between May and September 40% of the time, falling an additional 1.5% on average in that period. It fell 40% of the time, so it went up 60% of the time? Investors should try to trade around an average 150 basis point decline that may or may not happen next time and possibly pay taxes? Like I said, insanely bad advice and they did walk it back. 

My approach on this sort of thing has always been to add funds with negative a correlation to the stock market to try to reduce the portfolio's volatility as opposed to doing a lot of selling. In past cycles, I've done a little selling at points like now but on this go around, no selling thus far, just increased hedging. If the market goes down a lot, we're not there yet, then the hedges will grow relative to the portfolio to hedge more, in a sense they are dynamic. If the stock market rockets higher, then yes the hedges will be a drag but we won't miss a rocketing up. Part of the shift away from selling might be that there are many more choices for products that hedge. They shouldn't all be expected to work perfectly every time, but they work well enough for me to remain confident in them.

Finally, the cover story was about ESG investing and the funds that offer ESG exposure. Nate Geraci (a great follow on Twitter for ETF info) Tweeted that Barron's took ESG to the "woodshed" and he cited this line from a report by Ken Pucker and Andrew King from Boston University that said: “The logic and evidence for assurances of ESG-driven alpha are lacking. Indeed, it is our best guess that flows of money into ESG funds represent a marketing-induced trend that will neither benefit the planet nor provide investors with higher returns.”

I've never considered ESG funds. I think they are a marketing gimmick and a fee grab. Note, I am not against the concept of avoiding companies that you think are bad actors or that pollute the planet or any other issues important to you. Believing you should avoid cigarette companies can coexist with the idea that the ESG funds being cranked out are marketing gimmicks and fee grabs. The closest I've ever gotten to an ESG conversation was a client where the wife said I don't want to own an oil sands stocks. The husband didn't care and she was ok if the oil sands stock was in his IRA not hers. 

I want to stress, this disdain for ESG funds has nothing to do with my wanting a healthier planet, even if I'm not sure how to get there. I care about the planet, the funds are a racket. 

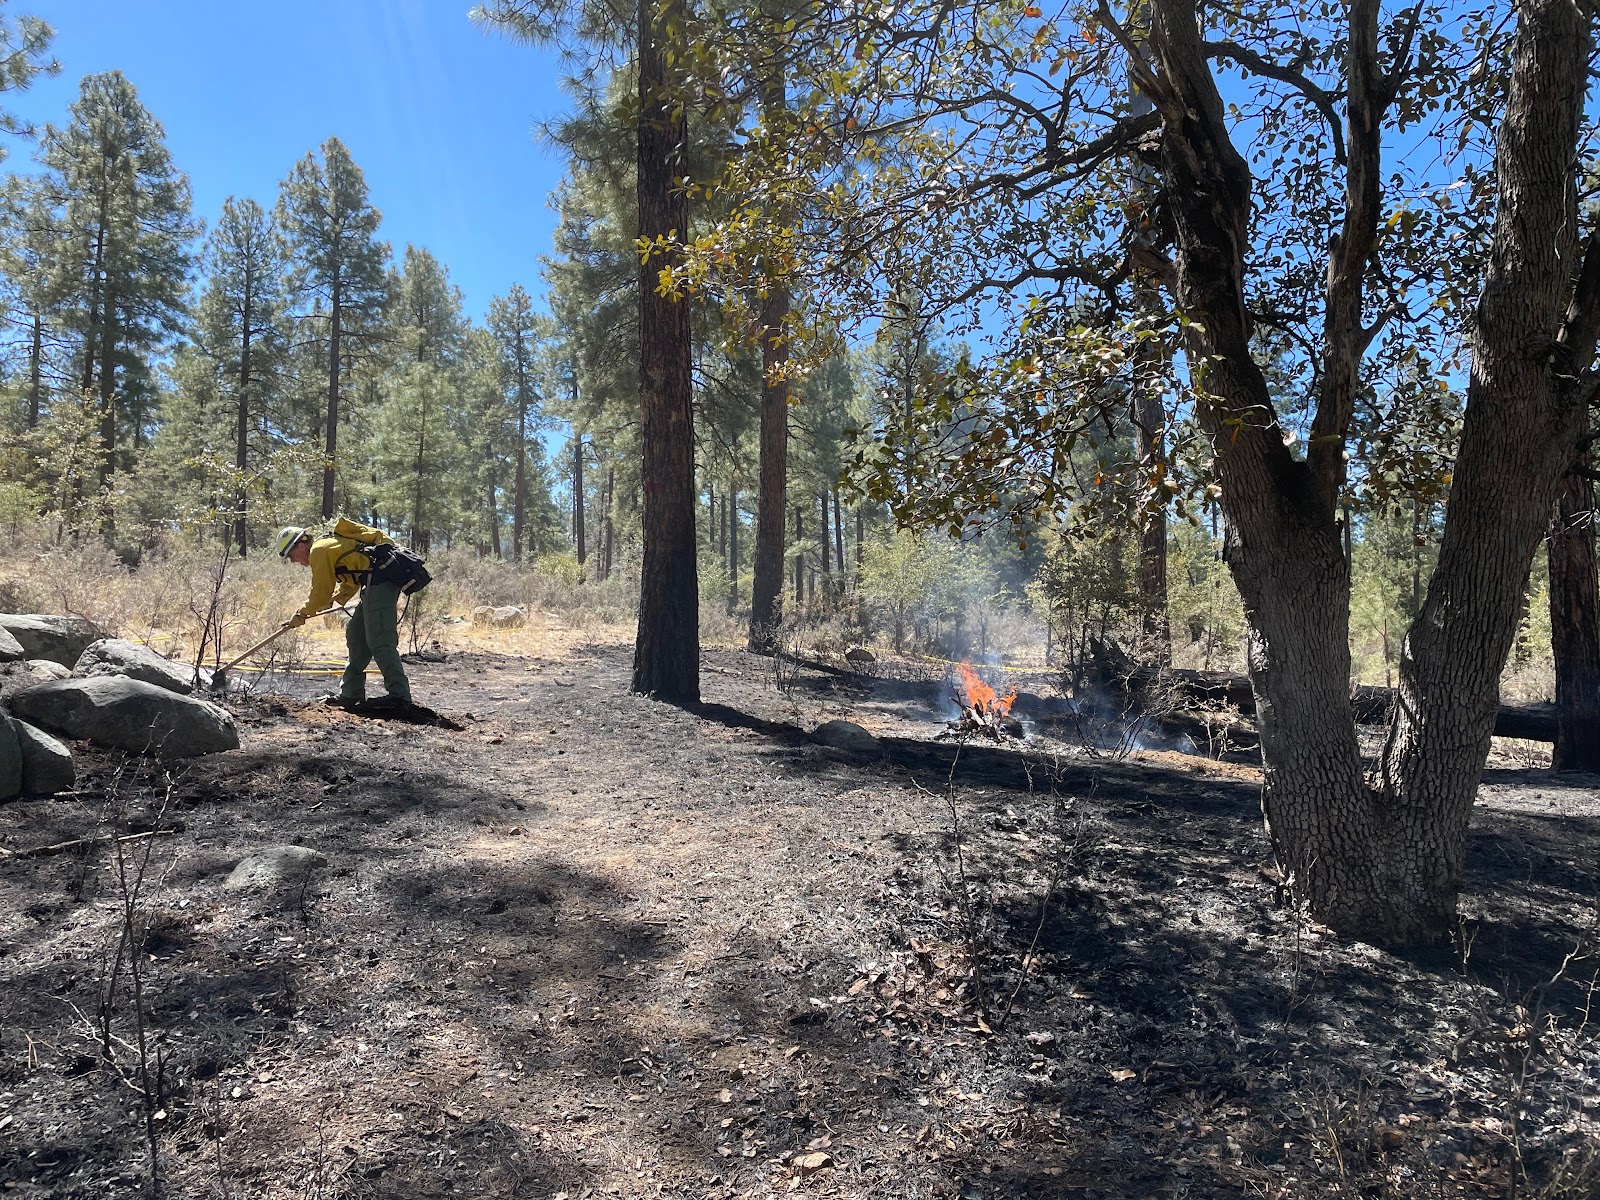
Here's a picture from a fun fire training we had today, simulating a wildfire out in the community. I'm toward the middle, by the door of the engine in the white helmet. 


Tuesday, April 12, 2022

Baseball Card Riches & Regrets

It's a fun thing for me when different "Twitters" that I follow or engage with intersect like fire service related Twitter and financial Twitter. And while there may not be a huge value add when someone in "critical thinking Twitter" weighs in on fitness, it is still interesting to me. There's an intellectual appeal to agreeing with someone on many points in one subject and disagreeing with them on many points in a completely different subject.   

Over the last few years, my childhood interest in baseball cards has been rekindled. There's a nostalgic aspect to this and I view the cards, many of them anyway, as little pieces of art. For purposes of this post, even if you don't get it, just remember that art is in the eye of the beholder, and that's how I think of many of  them as well as getting a kick out of it. 

I've been involved with Baseball Card Twitter to a small extent but got to do something very cool last summer, supporting the movement to have the MLB MVP awards renamed for negro league legend Josh Gibson. I entered a card art "competition" where a bunch of artists, and (ahem) one financial blogger had cards featuring Gibson made to raise money for the Josh Gibson Foundation and to raise awareness of Gibson's legacy. This is the card I had printed up. I still have a few available. You'd make a donation directly to the foundation, DM me proof on Twitter and your address and I will send you one. Note, I made no money from this, all proceeds went to the foundation. 


Earlier this week, baseball card Twitter intersected with personal finance Twitter as follows;


Hoping I could add value to the conversation I replied 

Slightly bigger picture is to live below your means. Have less house than you can afford, drive Toyotas for 20 years, don't carry CC balances. Related to cards, I buy inexpensive ones that I love. I can count on 1 hand the # $50 cards that I've bought, never more $$ than that.

It's of course basic common sense but I'm on board with repeating basic common sense. As I've followed the hobby along for the last couple of years I regularly see spending on cards that I cannot wrap my head around. Clearly, there are people who can spend hundreds or thousands a month or even a week on their hobby, on baseball cards, but that is far from the majority. 

Baseball cards have enjoyed a recent resurgence in popularity in part to money being cheap, people spending more time at home bored due to Covid and card provider Topps has been offering evermore cards and products to collect and financially speculate on including "art cards," first two years ago with Project 2020 and in 2021 Project 70. This is an example from Project 70. I think it's pretty clear it's art, even if it doesn't resonate with you at all.


Project 70 pushed out six "base cards" per day toward the end at $20 per card as well as artists proofs that ranged from $125 up to the high $200's from what I saw. Also mixed in there were autographed cards, some of which went for hundreds of dollars. All in, there were over 1000 base cards to buy and just as many artists proofs, although they were limited to a 51 card run versus several hundred or in some cases several thousand base cards.

I saw countless Tweets from people regularly ordering all the cards in a given day plus an artist proof or maybe two. This picture from the Topps website shows the difference between a base card on the left and an artists proof on the right. As best as I can tell, it's just the silver framing around the card.

I don't know why the silver framing would be worth $150 to someone. When you go to Starbucks for a latte, do you care if the Barista tells you it's $3.90 one day versus $4.05 another day? You probably don't care about the $0.15 and I can accept that there are people who don't care about $150.00 with the exact same logic but that's very few people, far fewer than the many people I saw loading up on Project 70 base cards and artists proofs. This seems like a different road to a similar bad financial outcome for a lot people. 

Hobbyists also buy new cards by the box or even by the case. Depending on how people buy, these too can costs hundreds of dollars and I get the sense that people buy a lot of new cards pursuing complete sets. There's also lots of money, hundreds again, on very limited cards with autographs or a swatch of clothing embedded in the card and so on. I just said hundreds. For certain cards of Shohei Ohtani or Wander Franco, make that thousands. 

Vintage have also gone up a lot in value. I think part of the overall popularity might be that it has become easier to learn about players from the past. I certainly feel like I know more about old time players, the negro leagues and so on and it's fun pairing that new found knowledge with a card or two or for some collectors, dozens and dozens of cards. Here's an iconic card, it's a 1953 Topps Jack Robinson.

If you look on eBay, you'll see these ranging from the mid hundreds at the low end to $3000-$4000 at the high end but if you pursued one with high grading through an auction house, they'd likely be much more. It's a neat card and I own a reprint of it that I spend less than $10 on, probably less than $5 but I don't remember. Hard core hobbyists might poopoo buying reprints but I don't care. I have four reprints, all in they were less than $20. Like with many (most?) hobbies there are inexpensive ways to engage.

Mel Daniels was an ABA legend (look him up), I've long been fascinated by the ABA. That card was about $12. Spriggs was a pretty anonymous player but the $5 card is stunning (to me) and the Henderson is a custom card which is a whole other thing, they're very cool, it cost $15. 

Tying in some things we talk about here all the time, someone making a fine living shelling out $1000/mo or even more for cards then turning 50 and getting a type 2 diabetes diagnosis resulting in $800 additional every month for insulin and then some other regular new expense and any margin for error disappears or worse someone goes in the hole because of a circumstance like this.

I can see where buying baseball cards can be addictive and accelerate into a more expensive hobby/habit. Back to the original Tweet that was the catalyst for this post, the time to prevent a problem is now, before there is a problem

Is there an investment angle to pursue? The argument in favor makes cards out to be an alternative asset class. It is, but my casual observation is that card price performance tends to be pro-cyclical which if correct means it correlates to the economic cycle and so also correlates to the stock market cycle. In that case it might just be a bet on outperformance. As an asset class, cards could certainly outperform but that to me is tricky. Do a search for "junk wax" to see what I mean. 

A few years ago I bought a 1970 Bobby Orr hockey card graded at 6.5 (the only graded card I have) for about $20. A few months ago I saw where a couple of them, with the identical grade curiously enough that sold in the $300's. I just saw one with a higher grade for sale for $550 on eBay. Sure, that's a great "return," better than stocks, kind of along the lines of Bitcoin from late 2018-early 2021 when it went up 10 fold. Even if I somehow knew that would happen (I didn't), was I somehow going to find 500 of them or 1000 of them to buy for that return? The answer is obviously no for several reasons.  

Fractional ownership of very high dollar value cards, almost like owning shares, is a possibility. It might be kind of fun to own a few hundred dollars worth of a multi-million dollar Mickey Mantle card or Lebron card (I don't understand 7 figure valuations on cards of current players like Doncic, Trout and so on). I would warn that fraud exists. I do not have to chops to assess a card as being a fraud but it should not be a black swan if some fractional ownership company or exchange is either the victim of a fraud or worse, perpetuates a fraud. 

For me, buying what I love (you'll see that phrase repeated in the common sense circles of the hobby) and keeping it cheap, I'm about the equivalent of a latte a day, is a safe way to engage, have fun, meet other people even if just virtually, learn and have fun (repeated for emphasis). 

Saturday, April 09, 2022

Simplicity Over Complexity

This morning we had a monthly board meeting for Walker Fire (this is the department where I've been  volunteering for last 19 years, the last 10+ as chief). Making idle chit chat, one of the board members asked me how our Airbnb rental is going, if we're getting a lot of bookings. 

We live at the end of our road, there's only one other cabin near us and it's kind of close. So the back story is that in 2017 we bought that neighboring cabin with the intention of renting it out on Airbnb. We did not want full time neighbors and we'd be just fine carrying the mortgage if renting it out failed.


The cabin is pretty neat and the views are epic, also the only reason anyone is driving by is because they're lost so it's a great getaway. Bookings were very good, then Covid hit and we benefited from get out of the crowded city demand so we're pretty much booked solid.  


Amusingly, we remodeled the cabin, bathroom and kitchen mostly, via a reality TV show on CNBC called Cash Pad. Part of the remodel and TV exposure was that we got better pictures for our listing and for several months our cabin was the first listing you'd see when you looked at Prescott on Airbnb, literally the first one. We are acutely aware of how lucky we are.

The board member at the meeting this morning was happy for us and half kiddingly said we should quit our jobs and buy a couple more to manage. We own the cabin next door on a little mountain that gets no traffic. We have one mortgage payment that's pretty modest and save for the occasional expensive repair, it's inexpensive to maintain. In short it is very simple.

When Covid ramped up a couple of years ago there were a lot of stories circulating about Airbnb hosts who owned dozens of properties, with mortgages of course, and how they were on the verge of bankruptcy after no time at all for having to make a bunch of mortgage payments. No matter how successful any of these were or were not, managing a dozen rentals, even half that, is a very complex enterprise. 

Two years ago, the 15 acre parcel next to us was put up for sale. The buyer, who saw our episode of Cash Pad before they bought which is kind of funny, planned to subdivide the parcel into approximately 3-acre parcels. We bought the 3 acre slice closest to us as a buffer, thinking it's not easily buildable although it looks like it would lend itself to a container house if we ever wanted to pursue that. If we did that and rented that out I think it would still be relatively simple, only modestly more complex.

As things are now, the income from the one rental is a lot, relative to our needs which are low for living below our means. It's a simple but robust fallback plan if we ever need it. 

I think this sort of simplicity should be sought out wherever possible. 

Let's talk about diet. There's nothing simpler than food with no ingredients like meat, fish, cheese and eggs. There's nothing to read. Compare that to the ingredients for Beyond Meat.


Seed oils, cellulose (which I'm pretty sure means paper) and an assortment of acids. There's no convincing me this is healthy. Seed oils, there's a bunch of them listed there, are obesogenic and promote inflammation. It's a complex amalgamation of chemicals. It may not be realistic to avoid all processed food but building meals around simple food with no ingredients is an easy way to reduce your exposure dramatically. 

This can be applied to just about every aspect of life, seeking simplicity when possible. Since this is an investment blog, it is common for people to make investing far more complicated than it needs to be. It can be as simple or complex as anyone wants to make it. I can believe that one person's complex is another person's simple so the way I would think about it is to say that for most people, they should think their investment portfolio/process is simple. I certainly think that of my process. 

Simple does not mean no engagement. In the context of a 60/40 equities/fixed income portfolio model, having 40% in some sort of aggregate bond fund has been a very risky position. Rates have been rock bottom for ages, I have no idea if this current spike is the big one but anyone who has bought an aggregate bond fund in the last however many years bought high and now the price is going lower. In the first quarter, bonds did worse than equities. I've been writing about this forever. The decision to avoid buying high is obviously an active one and can happen in a two or three fund, simple, portfolio. 

Two or three funds is a little simpler than I want to go but is absolutely valid even if not always optimal. If I wanted that simple of a portfolio, at my age or older I'd probably set two years of expenses aside to avoid sequence of return risk, I'd have most of the portfolio in a broad based based equity index fund, some in a an alternative that is a reliable bond market proxy but that doesn't take interest rate risk and a narrow slice in asymmetry, some sort of crypto is an easy example of asymmetry but not the only asymmetric investment out there. 

Again, that's not set and forget, it's merely simple. Like any portfolio, it needs to be combined with an adequate savings rate, suitable asset allocation and the learned ability to not panic. 

Thursday, April 07, 2022

A Blogger Looks At 56

Part of the history of my blogging is to say it’s a look over my shoulder for anyone whose interested at how I manage client portfolios and also the process of aging as I started blogging at the original site in 2004 when I was 38. I wrote similar posts at 40 and 50 and then thought I’d go every five years and wrote one last year at 55 but somehow now, it seems like a lot can happen in a year and so what to capture how my thoughts evolve either quickly or slowly on certain things. If anyone is interested in that and can learn anything, all the better.

Fifty-Six is well past the age where you should understand how on track you are or are not for retiring or whatever comes after your primary career, assuming you even want to retire. Not everyone can be on track at 50 or 55 or 60, I am saying though that you should know where you stand.

For the last few years I’ve thought about my readiness to retire (I have no desire to retire) as follows; if my hand was forced in some scenario that I can’t envision, could we last, financially until 62 before I could take Social Security? If the answer is yes, how much longer past 62 could I last in line with my preference to take Social Security as late as possible? A lot would have to have gone wrong for me to be in the position of trying to figure making it to 62 or 66 or whatever to take Social Security.

Julie Biel, a portfolio manager at Kayne Anderson said “you can’t predict, you can only prepare.” It’s a far more succinct expression of a point I’ve been making for years. I’m not trying to guess what might go wrong, just trying to be prepared if something goes wrong. If things go seriously sideways, how resilient are we? That’s what I care about, I’ve written about this countless times because I believe it to be a crucial component of financial planning. What is your Plan B? Should you have a Plan C?

If you’ve been following along for the last few years you may have noticed I care a lot more about health stuff. I’ve always cared about health, I have always lifted weights and stayed in shape but I knew nothing about diet as it turned out. At 50, I was prediabetic. It took me about 10 minutes to find out about low carb eating, I started the day I got my diagnosis, reversed the prediabetes right away and lost 30 pounds I didn’t know I needed to lose.

There is no malady that exists where low carb hasn’t been studied as a possible treatment or tool to better manage that malady. I’m not saying it cures everything but if you do the research, it cures a lot and again, if you have some condition, I promise low carb has been studied. The odds of things going wrong medically go way down when you build muscle mass and lose fat around your mid-section. There’s too much here to go into greater detail but I am glad to talk to anyone about this, I’ve also created a list onTwitter that you can follow but I am convinced that low carb is a miracle.

But there is a financial planning aspect to this that I connect to in posts all the time, which is the money you’re not spending on prescriptions and doctor’s visits. On your insurance, how much would you have to pay for insulin? For some people it’s hundreds of dollars/mo. Someone in one of my circles takes a medication for seizures (there’s research on low carb for seizures). As I understand his insurance, once he exhausts his benefit, he has to pay out of pocket and it’s a little under $1000/mo for what I think is 9 months of the year.

How much money do you make? How much can you afford to spend on new “age-related” prescriptions? Someone making $10,000/mo, a fine living I think, might net somewhere between $7000 and $8000. Having to shell out $1500 for prescriptions sounds like a lot of money to me, it sounds problematic to me. We can’t be assured of the outputs we want but we can control the inputs, do what we have to in order to have the best chance of the outputs we want. Lift weights and cut carbs. I know most people will not do these things but they are making their lives much more difficult. At 56 and 50 we have no prescriptions and save about $1000/mo going with crappy health insurance because thankfully we can get away with crappy health insurance.  That’s real money we’re not spending all through our 50’s…hopefully longer. I see more and more advisors getting on the bandwagon with me trying to promote healthy habits because it absolutely is a financial planning issue. Circling back above, if my hand was forced out of my work, having to spend $1500/mo on health insurance and another $1500 on prescriptions would be a serious financial threat. And then what are those $1500 items going to cost in two years or four years? Poor health is a serious financial threat.

Quite a few of my followers on Twitter follow me for health stuff. Here’s an accountability thread with a little more detail if you’re interested.

I’ve come to care more about optionality and resilience over the last few years, writing about them more frequently. The world seems like it’s gotten crazier and I want to be less vulnerable to whatever craziness ends up meaning. The financial implication is a newfound willingness to invest in convenience. The simplest example of this was putting our house on solar with battery backup not because we fear some sort of post-societal outcome but the grid infrastructure where we live is old, like hard-to-find parts old, and it is not clear when or if they are going to spend the money to modernize it. The problem with a propane generator is that the propane company can’t drive up our road to make a delivery when there’s snow/ice and in the right (or wrong) circumstance, we could use all our propane running a generator for a week or so. We’ve applied that mindset to other things, other conveniences too.


I continue to cultivate my Plan B of working on large fires in incident management. I’ve kind of thought this door was open to me. It turns out that is probably is open, better odds than I thought is fair to say. If I do have that opportunity, it is for reasons I’ve been writing about for ages. I’ve given my all to the volunteer endeavor that I love doing for many years. I’ve been very involved in the Prescott fire community since before I became chief, I’ve been the chief for a little over 10 years now.

When I’ve written about monetizing your hobby, I talk about taking a long runway and that’s what I’ve done with the fire department. It’s important to walk the walk.

The last thing I’ll hit on is investment philosophy. For personal accounts, I have come to have a greater appreciation for the stock market’s ergodicity, that no matter how much or how little we do, the stock market will continue to work from the lower left of the chart to the upper right. Maybe at a slower rate, maybe at a fast rate but either way that will continue. For clients, many holdings have been in the portfolio for more than ten years which is a nod to ergodicity but I am also focused on reducing their volatility so that their income needs are not disrupted when the stock market does something crazy.

The world may continue get even crazier. All of the above priorities could maybe be summed up as knowing when to be orthogonal to what everyone else is doing, trying to do all I can to navigate to all of the outcomes we want for ourselves. 

The picture is from last weekend, I'm mopping up at drill that had live fire. 

Sunday, April 03, 2022

Miserable Underperforming Managed Futures Had A Banner Quarter

RCM Alternatives posted a quick note highlighting the strong quarter put in by the managed futures strategy. Very simply, managed futures is a trend following strategy that usually involves commodity futures and can also involve currency futures, financial futures, not usually equity futures and I believe it is correct to say not quite yet for Bitcoin futures but maybe that will come.

I've been interested in and writing about manage futures since before the Financial Crisis. Back then the only fund I was aware of was the Rydex Managed Futures Fund (RYMFX). That fund still exists but has had a name change or two and is now known as the Guggenheim Managed Futures Strategy Fund and still has it's old Rydex symbol. 

I was first attracted to the fund because the strategy has the tendency to have a negative to low correlation to equities. So when equities go down it should hopefully go up. If that's true, and it has been, then when equities go up, managed futures could very well go down which it has most of the time. During the raging bull market that started after the Financial Crisis, managed futures' performance in nominal terms has floundered. I saw quite a few articles over the years bagging on the strategy saying it no longer worked. Several times I wrote about or Tweeted that if you understand correlations, something that is supposed to have a negative to low correlation to equities is going to do poorly when equities do well so it's pretty much done what it's supposed to do the vast majority of the time. That sort of reliability is a fantastic attribute even if it's a suboptimal holding. 


So after a rough quarter for equities, checking in on managed futures makes sense and not surprisingly, when equities went down, managed futures went up. It's no better than it was, it has continued to maintain it's negative to low correlation to equities. 

This background allowed me to immediately understand BLNDX (client and personal holding) that I've been writing about for a little over two years and to immediately have faith in the strategy which is to blend equities and managed futures in one fund. 

One wrinkle that could give a boost to managed futures is interest rates on T-bills. The nature of a fund that uses futures contracts is that it will have a lot of cash in T-bills. Part of the long term performance going into the Financial Crisis came from T-bill yields that no longer exist but might be coming back. Go to Morningstar's year by year returns for the fund and then (sort of) counterfactually add another 200 basis points or 400 basis points whatever you think could be coming from T-bills when the tightening cycle ends. While simple extrapolation is too simple it likely adds basis points to the return every year. I should note though that while I believe there is something to this idea, the two or three experts I've asked about this over the years have all said they didn't think this was noteworthy. I disagree but I could be wrong. 

I threw gold into the chart because it should go up when equities go down and while it does not always do that, it did in the first quarter. I always say gold tends to go up in down markets more often than not and often enough for me to believe in it. Bitcoin is in there too, showing IMO there is nothing reliable about it in a down market for equities. Not that you shouldn't speculate on it just that for now it doesn't really hedge anything.  

Thursday, March 24, 2022

The Mistakes Of The Great Resignation

Barron's looked at the reversal of the Great Resignation that appears to be underway. The Great Resignation was the pandemic-induced phenomenon where people quit their jobs or retired early for feeling scared of the pandemic, emboldened by stock market gains and motivated to reassess their priorities as many people were getting sick and even dying. 

Toward the end of the article was an anecdote about a now 50-year old who had "retired" in February, 2021 but found himself bored after a while and feeling some financial stress after seeing his portfolio go down in value. It turned out to be a one year sabbatical, going back to his job in February of this year. He was quoted in the article "it's nice not having to go to work but what are you going to do?"

I say this a lot, you don't want to wake up on day one of...in this case, retirement and say to yourself, "ok, now what am I going to do?" There's a natural tendency for people to make things too complicated and a blind spot of mine might be that I make things too simple but what do you enjoy doing, what does your ideal day look like? How much of that ideal is embedded into your typical day already? If there's not as much overlap between your ideal and your regular routine, what can you do to change that? Building more of your ideal into your regular routine is a way to more easily transition into whatever comes after you move on from your primary career even if moving on just means doing the same work part time. 

One part of the Barron's anecdote was the implication that the guy played a lot of golf. I don't golf so I don't know how much green fees are these days. When I google "average green fees" $61 comes up as the first result. Is that realistic? How many rounds per week is the typical retiree going to get in at $61 per? I know clubs are expensive too. I might be cheap but this seems like an expensive hobby for a retirement plan that causes stress from a portfolio decline of some magnitude during an up year for the stock market--presuming 2021 since he was back at work as quick as February.

How old are you? If you want to retire, when do you want to do it? That's how much time you have to figure it out if you haven't already done so. I get that many people don't love what they do for work and want to retire from it at some point. What do you love? What would you want to learn about as something new? Learning new things is critical to successful aging and there are plenty of outlets to go learn new things. What are you passionate about that needs volunteer help? Hopefully any planning like this leaves time for exercise too.     

I said many times before, and I think the Barron's anecdote is a reiteration, that retirement planning isn't just financial. Knowing yourself and what you want to do and what will make you happy are key to getting retirement, or whatever you call it, right. This is why I write so often about the non-financial aspects of retirement so frequently. 

Tuesday, March 22, 2022

Gameplanning For Crazy Inflation

Two weeks ago, I put gas in our Tundra for $3.94/gallon. A couple of days later my wife filled her 4Runner for $4.19/gallon. This past Sunday, I took our gas cans to fill them up--we keep 12 gallons on hand for our ATV and to have in a pinch--and paid $4.34. Gas in Prescott tends to be a little lower than the national average.


In the context of preventing/solving problems and connecting to my comments the other day about the crazy cost of insulin, would $10 gas be a problem for you? If so, how much of a problem? Would it be a problem so big that you'd need to make changes to some part of your routine? 

I don't think $10 gas is a serious threat as an average but what about $6 as a national average (that might take California close to $10)? My Tundra holds 26 gallons and if I typically fill it when it is only 1/4 full then that would work out to $195 to top it off at $10 per. My wife drives out to the United Animal Friends (the animal rescue she's the President of) ranch a couple of times/wk and that is on our nickel. She doesn't need to fill up that often but more than I do.

At $200 a pop and having a regular commute, that could easily be very problematic for a lot of people. I maybe fill once a month thanks to working from home and using a fire department for most, not all, trips into town. I also take the FD vehicle when I go work out at the fire house believing that if I am at the fire house for any reason, I should be immediately available to respond to a call as opposed to going home first and then responding. 


I am acutely aware how lucky we are on this front. If the price of gas became problematic, my wife could cut back to once/wk and we could both be strategic on grocery runs. So we've thought about it, assessed how much of a problem it is or is not and have a couple of thoughts on what we could do differently if we had to.

Not everyone is that lucky.

What about price inflation for food? I can't envision the scenario where we'd cut back on meat, eggs, fish, cheese or coffee. Those items, well maybe not the coffee, are crucial for good nutrition as we see it. We could cut other stuff...painfully...if it came to that. The fiat food that I wrote about the other day, as crazy as I might have thought that was 10 years ago, I'm not sure now but either way filling up on flour and corn products is insanely unhealthy and we'd sacrifice other things before food.

How vulnerable are you to increases in healthcare costs? The more visits to the doctor and the more prescriptions you take the more vulnerable you are obviously. We talk all the time about behavioral changes to try to reduce reliance on the healthcare system beyond what has happened to all of us over the last 15 years or so with the cost of health insurance. If my wife and I went with "good insurance" we'd be shelling out $1500/mo, we are lucky that we can get away with lousy "insurance" for a little over $500/mo. 

What other things do you spend money on that you have to? Can you cut back if you had to? What about discretionary spending like cable/satellite TV? Many people have moved on to streaming through their ISP. That doesn't quite work for us due to limited choices where we live but we could cut Directv if we had to but probably not internet service....unless I spent all day, every day at the firehouse. 

I have no idea what will happen. $10 gas as well as similar prices increases for other things seems like a crazy outcome to me but what if it happens? Or what if people get subsidies to help with those costs but you make a little too much to qualify for those subsidies. 

Do not wait until gas is at $10 to figure out how you'll handle gas at $10.

Monday, March 21, 2022

Alternative Expectations

David Tracey opined that "this is the worst market in my life that I've ever seen at pricing in risk." 

Is the equity market mispricing risk? Aren't markets efficient at pricing in all known information? A while back I quipped the markets are efficient except when they aren't. It's funny but it's kind of useless in terms of relying on rational actors in markets. It is useful in terms of pointing out we should not rely on markets always being efficient. Once you can accept that markets will behave irrationally, especially in times of headline stress, it gets easier to keep your cool, to not submit to emotions you might feel.

This contributes to my belief in and use of alternatives to try to manage portfolio volatility. I first learned about this concept back in the late 90's reading about then Harvard Management CEO Jack Meyer investing in timber land, actual timber land not some sort of exchange traded product or REIT, because of its low volatility and low correlation to equities. 

Everyone draws their own conclusions of course but I think alternatives, the right alternatives, properly sized can go a long way to helping smooth out the ride in times of market turmoil like we've been experiencing lately. Maybe for now it's not so much the market that's in turmoil, it's not really down that much, but the world, the headlines, the nature of the unknowns are the source of turmoil. 

I spend a lot of time learning about new (to me) funds and strategies that might help with client portfolios. It's a lot of fun for me but as I have mentioned before, I learn about way more funds than I ever use. For example, I have bee intrigued by risk parity since I first learned about it. I can't quite come around though to being confident in a strategy that balances out risk by levering up on bonds to balance out the risk, to create the parity of risk. With rates so low, even if they stay low the strategy calls for using leverage to buy high. 

This morning I stumbled across a portfolio of alternatives called Return Stacked 60/40 Absolute Return Index. Here's a summary of what they're trying to do: "The Index is designed to preserve exposure to core stock and bond allocations, while bolstering expected risk-adjusted returns with non-correlated return streams like trend following, global macro, and tail-hedging strategies. The Index targets a volatility and drawdown profile similar to a U.S.  balanced portfolio. Of course, there is no guarantee that the Index will meet this objective."

I'm not going to be critical but I don't exactly get what they are trying to do but they have good transparency on the alternatives that comprise their index. Here is a chart of the alternatives in their index YTD compared to the S&P 500 that is down 7% in the red circle.

Some of the alternative strategy funds are up and really don't look like the stock market this year (that's a good thing for an alt) and some are down like the S&P 500, or worse, and have offered no protection. Interesting to me is that TYA, a fairly new risk parity ETF, is down the most at 15.8%. Of course, yields have gone up so a risk parity ETF going down makes sense. But then, what is the value of it as an alt? Maybe there's a better argument for it as a portfolio proxy instead?

Generally, a three month sample size it pretty small but give or take, that's how long the current event has been going on. Zooming the above chart out to four months, the S&P 500 shows down 4.8% with only three of the alt funds charted outperforming and five underperforming. I would note that at four months, the chart for RDMIX appears to be distorted for a large annual payout. 

I disclose the alt funds I use all the time, regular readers know the names. I've lucked out maybe in this event as only one alt fund in my ownership universe has been acting funky, it's not a catastrophe, just not really doing what I'd hope. I don't want to say picking alts is complicated. I mentioned that I spend a lot of time studying these which gives confidence in figuring which ones will meet the expectations they set. There've been a few funds that I have test driven before using for clients, some I end up using like BLNDX and some I don't like SPYC. SPYC is in the Return Stacked index. It owns the S&P 500 with a long strangle overlay (options terminology) to try to smooth out the ride and when I owned it and any time I've looked at it since it just looks like a proxy for the index. I can't see the strategic benefit. 

Taking time to learn and understand does not equate to complexity in my mind but portfolio construction is my primary job so I can give it the time. 

I will close out with what role Bitcoin could play as a diversifier in the context we've been discussing. As someone who owns a little Bitcoin, I would tell you that for now it does nothing. Sometimes it correlates with stocks (risk on) and sometimes it doesn't and there doesn't appear to be any discernable pattern to when it will or will not correlate with stocks or hedge inflation or do anything else but its own thing to eventually either go to a bazillion or go to zero. YTD, Bitcoin has taken a path that at times looks like stocks and other times not and done so with more volatility to arrive at a similar decline as the S&P 500. Of course tomorrow, or any given day, it could be up or down 10% for any reason or no reason. 

This is not an anti-Bitcoin comment, again I own some, but it sets no reasonable expectation for anything in a portfolio. I own it in case the touts turn out to be correct and it does go to a bazillion. 

Sunday, March 20, 2022

Fiat Food Is Here, What Are You Going To Do About It?

Teresa Ghilarducci wrote an article for Bloomberg about ways to reduce spending in the face of our recent inflation problem. The Tweet promoting the article bullet pointed taking the bus, not buying in bulk, eating lentils instead of meat and in the article she talked about thinking twice about expensive medical care for pets. This got torched on Twitter.

I like to read Ghilarducci's articles even though I disagree with where she is coming from philosophically. As best as I can tell, she puts no stock in self-sufficiency or taking action to prevent/solve problems. I take her as believing the government can solve a lot of our problems for us. Teresa, if this makes your radar and my take is wrong, I'd love to hear from you.

The Barron's cover story this week was about food inflation. The first paragraph included an anecdote about a 29 year old single mother who "is cutting back on fresh produce and meat in exchange for less-nutritious but cheaper items while often unable to find inexpensive staples like pasta."

Saifedean Ammous, author of The Bitcoin Standard and The Fiat Standard, wrote about this exact thing referring to it as fiat food. When I first heard about fiat food I just thought it was a reference to high carb food that is unhealthy, so pervasive in the standard American diet and making us so sick. It sort of is that but with a more insidious underpinning. The basic idea is that government policy, the Fed has a seat at this table too, is inflationary, it erodes our purchasing power on purpose forcing people to food choices like mentioned above, being forced to switch to unhealthier food that is cheaper in nominal terms but will make us sick and require we start taking medication to treat these fiat diet-induced chronic maladies. 

The idea of not buying in bulk because it is not cheaper? Is that anyone's experience? I couldn't put my finger on it but Joe Norman took that as Ghilarducci saying not to prepare for anything. That resonates with me. I've been saying since before the pandemic started that we're not accumulating a year's worth of food or anything like that but want to keep a couple of weeks ahead of our needs to avoid the type of hassle that goes with empty store shelves and other disruptions. 

It sounds conspiracy theory-ish, doesn't it? Of course it does but it is happening. Arguably the push many years ago for more seed oil consumption is also part of it. Drug companies supposedly were involved in the creation of the food pyramid many decades ago pushing more grains and other carby foods. Statins are part of all of this too, they definitely lower cholesterol but cholesterol is not what is clogging us up and killing us, it's the sugar (carbs). Statins are a huge money maker for the drug companies, huge money maker with some lousy side effects and that don't prevent heart attacks. 

Does this sound crazy to you? Maybe it does but look at where we are. Do your own research on carbs, statins and the rest to draw your own conclusion but this is where we are. We are sicker, poorer and not taught or even encouraged to solve our own problems. It has continued with Covid. Vitamin D, Pepcid, Oil of Oregano, low dose aspirin, Vitamin C and a few others provide plenty of protection (look for it online) against Covid and can coexist with anything else you've done for yourself in regard to Covid. I am not making an anti-vax argument, I am saying that where so many of us are sick with chronic maladies that make up more vulnerable to Covid being serious, why wouldn't you do more?

All this is essentially ground zero for how I've come to live my life and what I've been writing about almost 16 years now, the importance of preventing or solving your own problems. 

Someone close to me got very sick with Covid last year and had to stay in the hospital. In the process of getting treated they learned they have Type 2 Diabetes and had to start taking insulin. I don't know how much they make but I believe they make a fine living, not a ton of money but a fine living. I don't know how much, if anything, they need to pay out of pocket for insulin but some people are paying hundreds of dollars per month. Think about that new expense combined with now paying 30% more for food, 40% more for gas, I don't even know how much natural gas/propane has gone up for heating your home and so on. 

This link had insulin costing $450/mo back in 2016. It's gone up since then of course and it depends on your insurance coverage, how much you actually pay. Could there be scenarios where people are paying $800/mo now? And their food bill just went up and all the rest. Ammous might refer to this as a form of slavery, fiat slavery. Could all of these things add up to an extra $1000/mo in expenses? More? Where is your limit on what you can afford?

Back to Ghilarducci suggesting lentils. According to WebMd, lentils have 12 grams of protein in a 140 calorie serving. That same serving also has a whopping 23 grams of carbohydrates. According to Very Well Fit, a 218 calorie serving of red meat, that's only 3 ounces, has 24 grams of protein and no carbohydrates. You'd likely eat more than 3 ounces of meat, maybe you'd eat about half a pound? For simple math, 9 ounces of meat would have 72 grams of protein. To get the same amount of protein from lentils you'd need to eat 4.6 times the amount of that original serving amount. Hold on though, protein bioavailability in beef is 92% compared to 70% (which is pretty good for a legume) for lentils so you'd need to eat even more lentils. If you want to try this, make sure you don't have immediate plans to leave your home. And eating that much lentils would be a carbohydrate festival making you a different kind of sick. She is promoting fiat food even if she is oblivious to the concept.

The realistic outcome of fiat food is eating less protein and more carbohydrates and seed oils. Given the history of the food pyramid and all the rest, there's an argument that this conspiracy theory may not be a theory. Best case, we've gotten to this point because of incompetence. 

Regardless of whether it's conspiracy or incompetence, we cannot rely on the people who got us here, politicians, government, food companies or drug companies, to fix it. It is up to us to fix it for ourselves, to prevent our problems from happening or solve them for ourselves when they do happen. No one will care more about our outcomes than us. 

Back to Ghilarducci again, her suggestions are reactionary to what is happening. Paraphrasing myself, you don't want to wake up on day one of a crisis and say "ok, now what am I going to do?" 

Living below your means and taking care of your health and fitness are both low hanging fruit in this conversation, I've been writing about that forever and living it even longer. All of the problems people, including my friend above, might be having now are a little easier when you are under mortgaged, or no mortgage, don't have car payments, aren't drowning in credit card debt and not shelling out $X00/mo for insulin. 

And the thing is, it's not too late. Here is information about a study that showed people can reverse T2D by fasting for 72 hours. Of course, anyone for whom that is successful would then need to change their habits. I'm not saying that would work for everyone with T2D, but why the hell wouldn't you try it? A slower path to the same outcome can be just cutting carb consumption significantly. Again, won't work for everyone but why the hell wouldn't you try? Lifting weights and skipping breakfast will give you more bang for your low carb buck. The body is very forgiving and it doesn't take long, you just need to do it.

Don't rely on politicians or anyone else to come up with the solution.    

Monday, March 14, 2022

Diversification Doesn't Always Feel Good

Cullen Roche rhetorically asked if 60/40 is finally dead. He was of course referring to the standard allocation of 60% into equities and 40% into bonds. He notes that bonds haven't really come through this year to offer ballast to the equity market declines. 

I've been writing about the flaws, as I see them, with 60/40 for many years. Yields have been low and going lower for many years until recently. The ten year US Treasury is currently in the neighborhood of a 2% yield which is higher than it's been for awhile but I would argue that even 3% for ten years is not very attractive. Of course if/as yields go up, the price of bonds and bond funds will go down. That is the risk when you buy fixed income at a high price (low yield). With a bond you will eventually get your money back, save for a default, but with bond funds there is no par value for the fund to return to. 

The relatively low yields more than 15 years ago pushed me to learn about alternatives, back then there's wasn't really a term for them so I called them diversifiers, that would help manage the volatility of a normal equity portfolio. Back then it was pretty much just gold, inverse index funds and a managed futures mutual fund. All three do a great job, IMO, of maintaining their low to negative correlation to equities so they do tend to go up when equities go down but they also go down when equities go up and equities go up the vast majority of the time. I don't want a portfolio of alternatives that are hedged by a little equity exposure. Equities go up most of the time, so I want to maintain an equity portfolio and am reasonably confident that the alternatives I use will do what they're supposed to in terms of hedging, more often than not. 


The chart shows most of the alternatives I use personally and for clients. I have been writing about all them for many years. BLNDX as possibly the newest addition is one I've used and written about for two years already. They are all up by varying amounts which helps. Early-ish last year I added a metals and mining ETF which has benefitted from the surge in reported price inflation. Of course we still have exposure to tech and discretionary and those are both struggling, doing worse than the S&P 500. 

It is crucial to understand that those things on the chart would probably all be underperforming the stock market if we were having another up year. BLNDX has at times kept up with equities and there was a stretch a couple of years ago or so where BTAL also kept up but that is not the expectation for either one. 

A good way to think about diversification is to ask yourself, if everything you own goes up together in a bull market, what is likely to happen when there is a bear market? They're likely to all go down together. You've diversified issuer risk but not market risk. My objective, as I have always articulated it, is to try to avoid the full brunt of large declines not to miss those large declines entirely. 

For now, the S&P 500 isn't really down a lot, it's only down a little. I am concerned that this could turn into down a lot so this morning I added to clients' existing position in SH increasing our hedge. The catalyst was not the death cross that looks like happened today but that the 200 day moving average is about to turn lower any day...maybe that happened today too. I took all previous action in regards to hedging with diversifiers long before the SPX breached its 200 DMA because certain risks seemed very high to me, risks having nothing to do with Russia invading Ukraine, that was not on my dance card early. 

One behavioral issue with these types of funds is that on the way up, you own too much and on the way down you don't own enough. On thing though is that if equities really puke down, I think at least a couple of the above mentioned funds could go up a lot. At some point, hedges need to come off, you don't need to protect against a large decline after a large decline, and those proceeds can either buy back in or be used to meet client income needs. If the market rockets higher starting tomorrow, then yes we will lag a little but not miss it--see own too much up above.  

Wednesday, March 09, 2022

The Value Of Being Financially Resilient

In an article about retirement withdrawal strategies, Richard Connor looked at a variation I'd never seen before where the idea is to mirror the IRS tables for Required Minimum Distributions (RMDs). The most common approach to retirement withdrawals, more like the most common philosophy, is the 4% rule which says in your first year of retirement you take 4% and then adjust up every year by the rate to inflation so if inflation runs at 3% you'd take 4.12% the second year and then reevaluate every year thereafter. 

It's difficult for me to believe too many people pull out the CPI number and then adjust their withdrawal up by that amount. If you know anyone who does that please let me know. What is more realistic is people who take a regular distribution start with some fixed number that's somewhat close to 4%...maybe...stick with that as long as is practical and then at some point that dollar amount will change based on client need and chances are that number will go up, not down.

What I've written about as building block is whatever you got, 4%. That's a slight tweak on the 4% rule that throws out the inflation math because as the portfolio goes up, as it inflates, it will hopefully keep up with inflation. The more practical application would be 1% of your balance every three months. 

The RMD strategy that Connor wrote about might be thought of as a middle ground between those three ideas. The way this works is you look at an RMD table, look at your age and divide your portfolio by the factor associated with your age. The amount you take goes up every year as your life expectancy decreases. With a $500,000 portfolio, at 72 you'd take $18,248 ($500k/27.4) and with the same amount at 92 years old you'd take $49,019 ($500k/10.2). At 114 years old, you'd take half of what is left. 

You have to take the RMD if you have a traditional/rollover IRA. You don't have to spend the money, you just need to make the withdrawal from the IRA so the government can collect taxes from you. 

Scaling up your total portfolio income up in line with the RMD table makes sense math-wise. If you make it close to 90 and have been able to stay on plan with your withdrawals with no plan-altering large expenses then you can get away with taking more out.

I do question how practical this is though from one standpoint which is that retirees tend to spend more money early on in retirement, then spend less as they get older and then spend a lot more when they are considerably older and most likely to need some sort of long term care. If I am reading this link correctly, 37% of us will need some sort of care from checking into a facility. A long time ago, there was a rule of thumb that long term care facilities were designed to take your last $200,000. With inflation, maybe that's now $300,000.

Quick detour: no one wants to end up in a facility. Our best chance for avoiding that outcome is to lift weights to avoid becoming physically frail and to greatly reduce carbohydrate consumption to avoid getting sick. Carb consumption has been studied in conjunction with every malady there is. You should draw your own conclusion but I've said many times before that I am living my life in belief that sugar, not anything else (other than cigarettes and drugs), are at the root of all medical conditions. Don't take my word for it but there is endless research for you to find and learn from to draw your own conclusion. 

Tying in a rule of thumb I made up, being 85, healthy and out of money is a tough spot to be in. Money is optionality. In the phase of life we're talking about that optionality can protect against the unexpected. You could be otherwise fit and healthy but have something medical come up that for whatever reason is expensive out of pocket. It will become increasingly common that 70 year olds will have to care for their 100 year old parents. You may want to move closer to someone (family) or something (National Park or hobby center) which ends up being expensive to do. Maybe you want to invest in a grandchild's startup which might be more of an act of love than a true money maker.

These sort of life events are why I write about optionality so frequently. You never know what you'll want to do in the future or what you'll have to do. While things like the 4% rule and the other variations are handy, my wife and I hope to be as independent from our portfolio as possible if/when we "retire." Things like post retirement gigs monetizing hobbies or some sort of passive income if you're lucky enough to create that sort of stream or finding work you don't want to retire from all serve to reduce the burden off of your portfolio which gives you more optionality later. 

A scenario of retiring healthy at 65 to do some sort of fun work that covers your expenses without needing to take from your portfolio or take Social Security is a great spot to be in. Especially if you love the endeavor and stay healthy enough to do it for awhile.

Just a couple of good decisions/habits early on can get you to that outcome. I of course concede that plenty of people do not want that outcome because it probably means dying with a lot of money in the bank. You've shorted yourself somehow, the thinking goes by dying with a lot of money. There's value in enjoying your money but there is also value in knowing you're financially resilient. I would encourage knowing the difference so you can choose what's best for you. 

Tuesday, March 08, 2022

Cultivating Your Side Hustle

An article in The Wall Street Journal cited a study from Zapier done in December 2020 that showed 1 in 3 people had a side hustle. Hat tip to Michael Batnick who called BS on the data, I jokingly replied to his Tweet that Zapier surveyed Uber drivers. 

Who knows how many people have a side hustle but I think just about all of us should be investing time to cultivate some sort of hustle as a back up plan in case how things are expected to go don't work out for some reason, some completely unpredictable reason. 

You have 30 years in at a company that cannot fail but does anyway and you're 58. You probably should have a backup. You're forced to get a vaccine by your employer (stale example now maybe but a big deal for some folks who did leave their work over this), you should probably have a backup. You work in some sort of highly specialized technology field and the tech goes through some sort of monumental change that is for you unlearnable (maybe not realistic, I don't know), you should probably have a backup. And 100 other scenarios, you should probably have a backup. 

I talk about this all the time because I think it's important. The term side hustle came to be long after I started writing about monetizing hobbies and although not quite the same thing they are related. If someone needs a second job then yeah they should seek something out and hopefully it is enjoyable. My primary context is more about cultivating a post-retirement gig in hopes of relieving the burden off your portfolio for a few years. If you've put in the work early on and then your hand gets forced like in one of the scenarios above then you're all the more resilient if you can get paid for a hobby and maybe even make it completely sustainable versus your monthly expenses. 

My backup of course involves the fire department. I literally cannot envision the scenario where I lose interest in the stock market and want to move on and being self employed should mean I determine my own fate but just because we can't envision something doesn't make it impossible. 


I have 19 years in with the fire department and hope to stick with it until I am very old. In all that time I've made essentially no money, a couple of hundred bucks ages ago, but the path monetizing it if I need to by working on large fires off district has been laid out for years and the department has taken steps in this direction lately so this is something I could just start doing. The way I maintain the opportunity is staying current with my EMT certificate and still being able to pass the pack test (three mile hike, wearing 45 pounds in 45 minutes or less). I have training for a couple of other things too that I could pursue. 

Crucial point of understanding is how much I love everything I do that is fire department related, I've loved it the whole 19 years and haven't cared about getting paid. That love for it, I believe contributes to some of the opportunity I have beyond being an EMT. 

If you love doing something as much I as love the fire department your odds of getting "lucky" with your unexpectedly needed backup plan go way up. I also think life is much better when you have an outside or extra curricular endeavor that you can give a lot of energy to. 

Friday, March 04, 2022

Correlations & The Long Game

Let's talk about gold. I've owned gold through the SPDR Gold Trust (GLD) for clients and personally since the 2nd or 3rd day that the fund started trading back in 2004. I've been saying the same things about exposure to gold since then which is 1) gold has the historical tendency to not look like the stock market, in times of equity market turmoil it tends to go up, not always, it's a tendency, enough of a tendency that I stick with it. And 2) if gold is the best performer you have, chances are things aren't going so well in the world.

Gold is not the best performer but the chart from Yahoo shows it up for the year just under 10%. 


I regularly see content and Tweets mocking gold because it has done so badly for the last however many years although for the last five years, Yahoo shows it up 56%. That's far behind the S&P 500 but it's not like it's down either. And if you look at a chart of any longish timeframe, you'll see exactly what I said. It tends to not look like the stock market more often than not. If the S&P 500 goes up 50 or 75% for the rest of the decade, I would expect gold to lag that by a lot but during the (hopefully) short windows of market panic I think gold will do what it usually does, that it tends to go up when markets go down. Not always but IMO more often than not. Diversifying with a little gold helps smooth out the ride during market events like this. 

Inflation is perking up of course. As a matter of maintaining a diversified portfolio, do you maintain any exposure to sectors or industries that tend to do well in an inflationary environment? If so, they are probably also up year to date. Holding on to a defense contracting company for the long term makes sense along the lines of gold for some types of crises like the current one also tends to be a good idea. Defense contractors tend to be procyclical so they should lag far less frequently than gold does.

The types of  hedges, liquid alternatives, that I write about so often which do lag when equities are doing well have also generally done what they're supposed to during this event, go up some or go down less. 

At some point the Ukraine situation will end, stocks will have stopped going down and start going back up. I have no idea when that will happen but it will and when that time comes all of these hedges and alts and inverse funds and the rest will probably go back to underperforming and that's ok. Over the long term, equities are the best performing asset class. Alts and hedges are meant to compliment an equity portfolio to smooth out the ride. For the long term, you don't want a portfolio of alternatives, hedged with a little bit of equity exposure unless you're in game over mode. 

If you don't want to be in the business of guessing when the next crisis will come, I certainly don't, then you might want to consider simply maintaining a position for the long term....for a little context I've held GLD for more than 17 years! I think that reasonably meets the definition of long game

Wednesday, March 02, 2022

The Only Definition Of Wealth...

JP Morgan is running an add where the tag line is "the only definition of wealth that matters is yours." The commercial then goes on to include different ideas like retiring early, or trading off a smaller house for a larger nest egg and other monetary ideas. 

Of course having some number in the bank you believe to be sufficient does meet a definition of wealth but I think the commercial misses the most important aspects of wealth. Once you get past the point of being able to pay for your shelter, to fill your refrigerator and other basic needs I would argue that just as important as monetary goals for wealth are health, time and optionality. They might be more important than monetary goals.

Whatever it is you want to do will be better if you (still) have your health. If all you want to do is be there for your grandkids, cool but no grandparent wants said of them "oh no, Grandpa can't do that anymore." For that person, wealth is being all in for time with grandchildren. If your hand is forced in retirement by having to work at a job you'd generally prefer not having to do, it will be easier if you're healthier and here I probably mean that you don't have the aches and pains that someone that age could otherwise have. And no matter what anyone wants to do or has to do, they certainly don't want to spend more than half a day a year in the doctor's office getting checked out. 

Time is another form of wealth. Setting your own schedule while you're still working is very empowering. Not punching a clock or answering to some sort of boss are also very empowering. When you set your own schedule it might make you less likely to want to retire. If someone spends years dreading some aspect of being an employee somewhere, even if the only thing they dread is their commute, then they are probably going to want to retire sooner than later. It's not that I am against retiring but sticking with work that you love does all sorts of things to promote successful aging in terms of social engagement, being challenged and having a sense of purpose. It also gives more room for error financially. 

I write about optionality all the time, it is a very important form of wealth. Optionality is something that most of us need to cultivate over a long period of time, I feel that way about myself anyway. I've played a very long game with the fire department and believe I have optionality to pursue some of the financial opportunities I've written about in the past. I don't think I will ever pursue them but they are there for me, it is optionality and it is empowering. I want to underscore that this has been a very long game for me. When I talk about monetizing a hobby I always say to figure out how to do it, if it can even be monetized long before you need to start to monetize it. 


The path here, if you've been an adult for a couple of decades is simple even if it is not easy. Live below your means (you'll save more), take care of yourself (cut carbs and lift weights) and stay curious enough to learn new things or get involved with new things. You never know where future optionality can come from. I've said all that before so I will add to that list to always do more than is expected, more than the minimum. I figured this out in college and that mind set has always led to experiences I would have never otherwise had or financial opportunities that although never led to millions, did help me build up a bigger cushion.

For younger readers, 45 or 50 or 60 or any age can be young allowing you to do all sorts of things you want to do or need to do. It comes down to a few good decisions early on and then sticking with those decisions to maintain your health, owning your time and your optionality. 

Thursday, February 24, 2022

Just Because Someone Is Paranoid, It Doesn't Mean...

Before the stock market opened this morning I sent a note out to clients about keeping things in context, that there have been more military conflicts than most people can remember and that no matter the outcome, at some point the decline will stop then stocks will go back up and eventually make a new high, we just don't know how long that will take. War is bad for just about every aspect of life but not necessarily bad for markets based on history. I reiterated that I have no idea what the sequence of events will be. We have things in place to soften the blow of large declines and I think they are generally working. 

And right on cue, the S&P 500 closed in the green....by a lot....

On to today's main point about general preparedness. I tried to prepare portfolios for market upheaval a while back, mostly over concerns of price inflation but not entirely. 

Today I saw a couple of Tweets that I found to be thought provoking. One talked about the possible seizing of bank accounts of Russian people by the Russian government if the US/Euro sanctions prove to be very effective. I have no idea if that possibility is real but that's not what matters. I can't get to the point of ever thinking the US government would ever do something like that but I would say the steps Canada took over the Freedom Convoy were shocking. 

The other Tweet said something to the effect that, this is not a 20th century conflict. Hacking would play a much greater role with the example used of hacking a train to crash. 

Now, marry those last two paragraphs together, some sort of hack where American's financial assets are not accessible for a time. I don't think theft is the likelier threat, more like not having access to bank accounts to pay bills or buy food. I don't know how concerned to be about this. I naturally tend to assign very low probabilities to these sort of threats but there's no reason to totally ignore this possibility either. Having a little cash on hand if nothing else certainly is convenient. Having $100,000 sitting around the house seems excessive but the convenience of just $50 runs out pretty quickly. Next level, have some gift cards (we don't have gift cards for this threat). Next level after that, have some Bitcoin. We have Bitcoin but not for this purpose. We own it for the asymmetric potential and I don't want to have all the time into learning about Bitcoin only to see the touts turn out to be right and not own any. 

I will say I am more bothered about being hackable. I'll take being called crazy but I want no part of having my house on the internet, appliances, door locks and the like, or having something like an Alexa listening to everything going on in our home. Our cars are kind of old but I assume they are not too old to get hacked. I readily concede how extremely remote it is to have you car hacked. Our ATV is not hackable for whatever that's worth. 

The bigger point is mitigating problems that you can foresee. In life, this could include the things above or getting a couple of weeks ahead on groceries at the dawn of Covid (before the pandemic was declared) which I wrote about back then. In portfolio terms, this means something I have been writing about all the way back to the first version of this blog which is owning a couple of things that have a low correlation to equities just in case you get caught wrong-footed by the start of decline of some sort. 

That used to be a little more difficult, you could buy gold. You can still buy gold but you can also use a bunch of other strategies that used to not be accessible in retail products. I write all the time about the ones I use which include GLD, BTAL, MERFX, TAIL and a couple of others. 

The barrier to entry for this sort of safeguarding, in life or your portfolio, is pretty low. I think you just need to think about it a little bit. What are the biggest threats to whatever it is you care about? Ok, how do you mitigate those threats. Often, my thought process will use the words threat and nuisance interchangeably. I wasn't really worried about there being no food two+ years ago but I wanted to avoid the nuisance of long lines at the store or substituting to the point of eating crappy food for a couple of weeks or so. If you shop at Costco, there's no reason to ever run out of toilet paper. Just don't wait until you're down to your last roll. This is pretty reachable for most folks. 

Wednesday, February 23, 2022

Don't Call It A Dip!

Barry Ritholtz was on Bloomberg for what I think is his weekly appearance and today's conversation focused on whether or not to buy pullbacks or BTFD if you know that acronym and a couple of other things. 

On buying the dip, I both agree and disagree with what Barry said. He said it is very difficult to time the bottom on theses declines that come along, very few people can do he said. I agree with that idea, it is difficult to reliably bottom tick a decline. Enough tries and yeah, you'll do it a couple of times but that is not a reliable methodology.

I do disagree with the framing of the entire premise. I would say forget about trying to guess when bottoms are in, don't think of it in those terms at all. A long time ago I said something like the odds of a large decline are a lot less after a large decline. When we're in the middle of a 20% or 30% or 50% decline, and of course on the way down there's no way to know where it will stop, you have a chance to buy at a very good discount. It's a good discount, it will still be a good discount even if it goes lower before going higher.

The habit of adding to equity exposure after a 30% decline is very likely to have a very good long term outcome, even if you're "wrong" for the next six months meaning it goes on to bottom at a 50% decline. Peter Lynch is instructive here, "I don't know what direction the next 20% is but I know what direction the next 100% is." The S&P 500 closed today at 4225. In 2007 it peaked at 1530. If you added to equities after the first 30% down, or 1071, does it today look like a good decision? The timing was not very good in the short term but handsomely rewarded nonetheless. 

If the current decline turns into something more serious and you can buy more down 30%, how good will that decision be 10 years from now? Pretty good I'd venture even if down 30% is just a stop on the way down to 40% or 50%. 

In Barry's appearance, Lisa Abramowitz asked Barry if his firm was doing anything different, if they were sitting on more cash than normal and he said no they weren't. I got the impression that they normally don't have much cash in client accounts but I don't know. What I will say is that I'm a big believer in setting cash aside for clients who are taking income from their portfolios. No matter where this current move down bottoms out, we know what will happen. The market will stop going down at some point and then eventually it will make a new high. We just don't know how long that will take.

Once someone really accepts that as true then they stop worrying about the market and start to turn their attention to making sure their portfolio income stream is not disrupted. The way I do things, that can mean having cash set aside or selling hedges owned for clients that are meant to go up when the market goes down. The need to hedge against a large decline is much less after a large decline. 

Friday, February 18, 2022

Don't Take Stock Tips From TV Touts

The following pictures were Tweeted into a conversation about Cathie Wood, Jim Cramer and Draftkings (DKNG) stock.


That's a chart of Draftkings puking down over a period of months. Supposedly, Jim Cramer yesterday said on CNBC that she (Wood) was buying the stock near $50 back in October and rhetorically asked "who would ever do that?"


If the second picture is real, apparently Jim Cramer would do that. I gave up on CNBC years ago, preferring Bloomberg TV. I have CNBC on in the background maybe an hour/week, otherwise Bloomberg.

I have no idea what Jim has ever said about Draftkings but in its short life as a publicly traded company it has been popular and widely followed. In rocketed higher for a time and how has been enduring a pretty long downtrend. For all of those factors, it is certain that Jim talked about the name several times. Where he spends many hours a day talking about stocks on TV, being asked questions, giving opinions, reacting to news, I bet if someone spent the time they'd find positive and negative comments from him about many stocks.

If someone wants to follow his advice about a given stock then arguably they can't afford to miss anything he says. I perceive him as being short term oriented, certainly much much short term than me, clients have owned some stocks for 15 years+. If you are short term oriented and interested in DKNG then you might have tried to trade that 20% bounce higher between Jan 25 of this year and Feb 1st and then that next slightly smaller bounce that followed. 

Some people are good at capturing those types of moves but that is trading that is not investing. Are you a trader or investor? I'm not saying being a trader is bad but what is bad is getting caught up in the excitement when a tout comes on to talk about what is really a trade and you, like me, are an investor. 

One thing that is important to me to understand about any stock or ETF I might buy is what its market attributes are, not the company, that's a different but obviously important thing, but how it behaves in the market. More volatile, less volatile? What, if anything does it correlate to or does not correlate to. In this context, Draftkings is heat, a lot of heat. It is volatility. When you buy the stock, even if you bought two years ago at $17 on the way to $60, you are buying volatility, you are making your portfolio more volatile, maybe a lot more volatile depending on how much you buy. 

If you have a diversified portfolio then you likely have some volatility in there and that's ok, I'd say it's an important feature in a diversified portfolio when properly sized. DKNG is not my type of holding. It's a good bet (see what I did there?) that sports gambling will remain popular but human emotion is such a huge component of the business model that I'd rather add volatility with other holdings. 

A while back I added a mining and metals ETF for clients. There certainly is volatility in that sort of holding but human emotion is not a first level component of pulling copper out of the ground. There's emotion in market pricing of copper, I accept that, but that is not the same to me if that makes sense.

So down all this way, is DKNG a buy? I have no idea and I am not a buyer but if we all accept that sports gambling is not going away, then I might wonder can sports betting go on without DKNG? The answer there is probably yes but DKNG has great name recognition. A small gamble on something down 2/3rds that you think won't disappear is not a crazy idea. If you do that regularly, you will be very wrong on occasion and of course very right on occasion. If you accept that, then you know that the next gamble you make could be the one you're very wrong about. 

That's a type of complexity that can be rewarding but that the typical investor just trying to have enough money when they need it (retirement?) probably doesn't need to speculate on.

Wednesday, February 16, 2022

We Should Probably Take Social Security Early

But I'm not gonna.

I haven't been able to post in awhile, I've been crazy busy across my various constituencies. We have a huge project with my day job and at the fire department we are working on the upcoming wildland fire season which includes spooling up to apply for a grant for a new Type 3 Engine which kind of looks like the truck below. That truck, one of our firefighters and I took a 36 hour trip to Missouri to look at it, it won't quite work but it's a stunning truck in great condition. 


To today's post. Yesterday a client asked me what my opinion was on taking Social Security early. I've been clear forever that I plan to wait until 70, or pretty close as a matter of the circumstance when the time comes, in case I die young, my wife who is 6 years younger would get the biggest payout possible. Other than that reason, the other big reason to wait is you get more in nominal terms every month. I said to my client "although I plan top wait, there are probably more reasons to take early than to wait." 

Arguments to take it early that I've seen made include that you're spending less of "your" money every month, thus letting your investment accounts get larger. There's no guarantee that you'll live past the point of breaking even. By breaking even I mean that if you wait until 70 and then die at 71, you'd have been worse off because you went all those years not collecting, so "they," the government, won. If you wait until 70 and die at 100 then you won, you end up with more money in the long run. The breakeven is around 78. 

If you don't know the math, every year that you wait, you're payout goes up by 8%. The payout at 70 is 76% greater than at 62. In the context of taking it early, I'm not sure 62, the earliest, is ideal but if you want to take it early, then you need to do some spreadsheet work to figure out what is optimal.

It doesn't make sense to take it early if you haven't retired from your career job because the payment will be reduced, maybe down to nothing depending on how much you make. You get it in the end but then, you might as well wait. 

If your full retirement age is 67 and you take it at 67 but you're still working then 85% of your payout is taxable as opposed to 50%....sort of. The 85% kicks in when a couple on Social Security makes $44,000+. Instead of paying extra tax, if you love your work at 67 and it pays well, you might as well wait. There's no advantage to waiting past 70. At that point you're giving money away, more precisely, you're giving money to the government. 

I think more people are interested in retiring as early as possible than people who want to keep working. Is that right? The reasons, related to successful aging, to keep working are many. Challenged mentally, having a purpose, having more optionality with what you've accumulated in your investment accounts, having meaningful interaction with other people, having the opportunity to keep learning (depending on what you do) and there must be others. 

Almost all of those things can be found elsewhere like very actively volunteering, monetizing a hobby or finding a second act career that pays much less but that you love. If you've been making $100,000 but can make it work with some sort of part time gig that pays $15,000 that you love, then taking Social Security makes a lot of sense. It may or may not be ideal relative to your specific situation but generically it certainly can make sense. 

Once you start taking it, if you take it early, you're not stuck. You can suspend it up to age 70 if after not working or making less money you get another high income job, you can suspend it and it will continue to accrue higher at that 8% annual rate. There is also a circumstance where you can pay back what you've taken to get a higher payout later. I've never heard of anyone doing that and it doesn't make a lick of sense to me why someone would do that. 

The most important planning tool is to figure out your priorities. Loving my job makes it much easier for my reason to want to wait. No one else should care about my priority but the utility is figuring out what matters to you. You want to retire early and draw it at 62, go for it...if you can swing it. If you don't love your work but you can't swing it at 62, then maybe 64 would work and in the mean time your payout would go up 16% plus a little more for the cost of living adjustment (COLA) and you might have been able to save more money in those two years.  

Incinerator Ridge Road

My wife and I went on a quick hike at the top of Mount Lemmon near Tucson. A few miles from the trailhead we drove by this road. I think TSL...