Sunday, June 16, 2024

Patience As An Investing Skill

We've all seen Tweets or notes in articles or other places where someone says something like $1000 invested in Amazon in nineteen ninety whatever would be worth a gazillion dollars today. Reactions to that sort of comment might be some mix of hindsight bias, regret and maybe a couple of things. We've talked about this before. The prompt today is a passage from Phillip Fisher shared by Koyfin that addresses the power of holding stocks, or now ETFs too, for a very long time. 


I'd never seen this before but holding on in the manner Fisher describes is something I try to do. My longest tenured clients have had some holdings for a full 20 years now and quite a few more names for 15 years. Holding a stock for than long will be challenging. Take a look at the long term chart of any stock you think has been a great performer for a long period of time and you will see some painful drawdowns. In 2018, Nvidia was down 30% versus 4% for the S&P 500 and in 2022 it was cut in half versus 18% for the S&P 500. The Nvidia example ties right in with the Fisher quote. 

Let's look at a couple of stocks compared to the S&P. Coincidental to the Fisher quote, I bought client holding Motorola Solutions (MSI) in 2013. The catalyst was a deadline for emergency services having to drop wide band radio frequencies in favor of narrow band which meant new radios for anyone still using wide band. A quick side note, this was not the only time where my involvement with Walker Fire helped with my day job. The other stock is Johnson & Johnson (JNJ) which is simply a very blue chip type of name which is one of the 20 year holds I have. 


When we talk about expectations for a holding, I expect something like MSI to outperform over the long term but not so with JNJ. Some of the drawdowns for MSI were far worse than the index. JNJ is far more of a yield story having been a 3-ish percent yielder for a long time so where Yahoo charts don't capture total return, you could add about 30% more to the JNJ result, still far behind the S&P 500. JNJ mostly stayed with the market but then started to disconnect around the time FANG stocks became a fad and has continued lately as we call those stocks the Magnificent Seven. 

For maintaining a diversified portfolio, the attributes of both stocks are important.
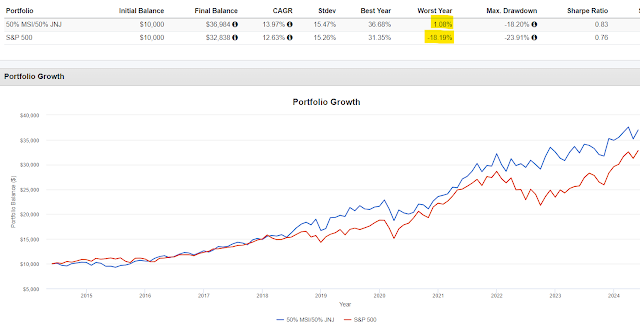

We know one name was far ahead of the market and the other lagged. The compounded growth of both is a little better which is fine but what is noteworthy in this study is the worst year. Trying to smooth out the ride is a big priority for reasons we've talked about hundreds of times, and up 1% in 2022 makes a great case for why a stock with JNJ's attributes is important to hold if you use individual stocks. In 2018, the 50/50 blend was up 12% versus a 4% drop for the S&P 500. The ten year result is competitive with the index but in 11 full and partial years available for us to look at, the 50/50 lagged the index six times.

Think about that. Slight outperformance long term but lagged in individual years more often than not. At the beginning of the post I mentioned the challenge of holding on for 20 years. This 50/50 we're talking about is a slightly different type of example that makes the same point. Can you live with that? That is the challenge of being a patient investor. 

Weak stock performance is going to happen and not a reason all by itself to sell if you're an investor as opposed to a trader. The next time the stock market drops 30-40%, I'd expect certain holdings like MSI to fall more and I'd expect some holdings to go down less (or maybe even up in a couple of instances). Don't frame this as infallibility because anything can happen at anytime, think more in terms of reliability. In 2008, JNJ was down just under 8% and in 2022 it was up about 7%. While that seems reliable to me, it's not infallible for future market events. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Friday, June 14, 2024

The Most Important Part of Portfolio Management

Randy Forsyth got on the capital efficiency/risk barbelling bandwagon in this week's column. Obviously I got a big kick out of that. Michael Hartnett from BofA apparently said something to the effect of 70% in T-bills "clipping" more than 5% and 30% in YOLO like the artificial intelligence theme. 

One of the comments, always read the comments, mentioned that this is what Nassim Taleb talked about doing ages ago. I got the idea from Taleb probably 16 or 17 years ago and enjoy writing about it. Taleb talked about 90/10 instead of 70/30 but it is the same concept. 

I wanted to try to model Harnett's idea of 70% T-bills and 30% AI. I did a search of AI ETFs at Vettafi and cherry picked the Clockwise Core Equity and Innovation ETF (TIME). As well as Nvidia and SMC have done lately, the ETFs are more inline with the tech sector, TIME has done a little better but quite a few of the thematic funds have lagged broad tech which surprised me.


In addition to 70/30, I tested how much TIME would equal 100% S&P 500. It turned out that a 39% allocation since the start of 2023 did the trick. With so much allocated to T-bills, it makes sense that the standard deviations of the barbell portfolios is so much lower. The 2022 results, not captured above are also interesting.


We can only get the last 11 months of 2022 but it is still interesting. TIME did far worse than the S&P 500 in 2022 but owning 30% or 39% in TIME, the rest in T-bills was not catastrophic.


The numbers are real but I don't know how realistic it is to think we can pick the best performing fund in a theme. There's a couple of layers there. First is picking the theme. That seems plausible but there really are a lot of funds on the Vettafi list that have done poorly. Great, you got the theme right but the fund chosen didn't capture the effect which is a serious risk to this concept.

This could be built simply allocating to high conviction ideas from several different parts of the market. I could backtest that with my top performers and it would look great and I could backtest it with names that have not done as well and the result would be underwhelming but realistically, if you split 35% between 5 different stocks, the results would be mixed.

The better takeaway is more along the lines of how risk is managed, maybe allocating a little to asymmetry to maybe dial down the volatility elsewhere in the portfolio or using alternatives to manage volatility and risk. It doesn't get said often enough but really, the most important part of portfolio management is mitigating risk.

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Thursday, June 13, 2024

Creating A Successful Outcome

A college buddy shared on Facebook that he is unexpectedly out of work and looking for a job. I know nothing of his financial situation so I am not talking about that. More generically, this is another anecdote of someone in their mid-50's who has had his hand forced. The reality is that it is not easy to find a job at that age, pretty much my age, that pays about the same. That might be unfair that we can't easily find jobs but I think people would accept that as mostly true.

This is going to happen to more of us. How vulnerable are you if this happens to you? If you don't think you have a lot of money saved, can you save more? Can you create an income stream somehow? How about more than one? We look at these things all the time so I won't rehash this again for this post but get started figuring this out now, before you need it, hopefully you never need it but the sooner you start the better off you'll be. 

Barron's wrote about expat living which is something we've looked at quite a few times. One aspect we haven't hit on but that Barron's looked at pretty closely is that it can take a while to create residency status in another country and even longer to gain citizenship. So it's another example of something retirement related where it is better to start early. 

There are plenty of places in Asia, eastern Europe and South America where people can live very comfortably for just a couple of thousand per month. Part of the equation is very inexpensive healthcare costs. I've questioned a few times whether the situation in Ecuador has gotten to a point that makes the country an inadvisable choice these days. Another college buddy is visiting there right now and he's posted a ton of pictures and video from Cuenca, although he is covering more ground than that, and if the political and gang related headlines are causing strife in day to day life, he doesn't appear to be finding any evidence of that. 

I will reiterate the idea though of keeping a hopefully paid off home in the US in case there is ever a need or desire to come back. The rent from a US property might cover all expenses in some countries allowing savings to keep growing and give more optionality on when to take Social Security. Even just a five year "adventure" to another country could have a hugely beneficial impact on retirement outcomes. 

Larry Swedroe had a long writeup about the LifeX mutual funds from Stone Ridge that we've looked at quite a few times. Basically, these funds turn into longevity pools at age 80, offering the potential for higher incomes than 4% from your own account. They are not annuities but they do annuitize the income stream. As opposed to be extremely expensive like regular annuities, these are merely not cheap although Allan Roth thinks the price is more than fair. 

As I have been saying, the concept of annuitizing without annuities is useful and Swedroe offers a couple of other points we have not explored here. Even if these are not the solution, they are at least a  step towards a solution.

A related idea that that tries but is not better than the LifeX funds is converting 401ks into annuities as we looked at a few weeks ago. Plan Advisor looked at whether target date funds could be converted into annuities. So, they are trying but I would run screaming from the room waving my arms frantically above my ahead if I was pitched a target date fund that converted into an annuity. 

There was an interesting point made though...interesting if it's correct which is that "participants already think some kind of guaranteed income is built into their plan." I'm not sure I believe that but if it is true, that would be a serious gut punch when they learn that is not the case. 

To the extent that "no one will care more about your retirement than you," actions like problem solving, learning about alternative forms of retirement living and keeping informed on investment product evolution is an important component to creating a successful outcome. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Wednesday, June 12, 2024

Wading Into Quantitative Investment Strategies

Bloomberg had a longish writeup about quantitative investment strategies or QIS. The very basic idea seems to be that it is in the neighborhood of being strategy replication. From the article, QIS are usually structured products or swaps that target risk premia with the following list of different strategies provided in the article.


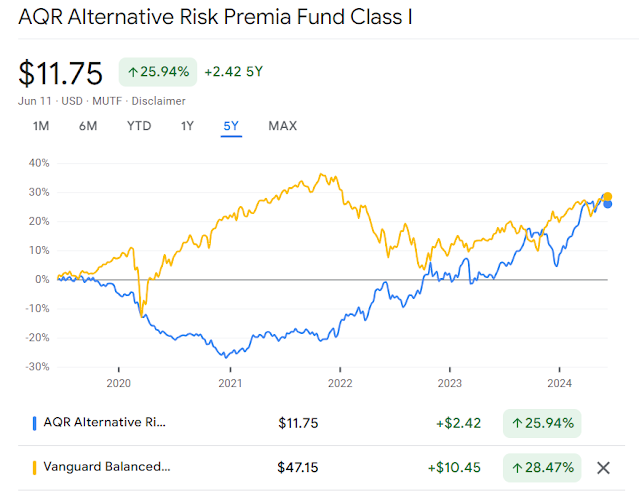
Risk premia is a fancy term often ascribed to alternative strategies. AQR has a fund called Alternative Risk Premia with symbol QRPIX. The text book definition is the difference between expected return on a security and the "risk-free rate of return" which is how T-bills are described. 


QRPIX has an interesting chart. It was negatively correlated up through 2022 and while the correlation is still negative, for the last year, both it and VBAIX are up over the last year with QRPIX having doubled the return of VBAIX in that time. QRPIX' standard deviation is pretty high for an alt, just a little less than VBAIX.

The Simplify Multi-QIS Alternative ETF (QIS) is a newer fund that would appear to be in the same arena. 


The chart tells you that QIS comes at it differently than QRPIX. Where QRPIX looks more like managed futures, which is one of the strategies used in QRPIX, QIS looks like it is trying to be a horizontal line that tilts upwards like merger arbitrage or convertible arbitrage. Simplify says the objective for QIS is absolute return with income so a result that looks similar to arbitrage makes sense to me. 

Bloomberg says that the QIS products from the banks, so the structured notes and swaps as opposed to these two funds, "come with a handbook about exactly how they work." Later in the article there is more conversation about the transparency. The literature for QRPIX seems somewhat transparent other than there is a lag but there is good color. The page for QIS seems to be less transparent.

QRPIX uses a lot of leverage to build a long and short book with strategies that include "equity, global macro and managed futures." There is also an aspect of risk parity. As of March 31, the risk, not the holdings, was allocated with 15.6% to commodities, 14.7% to currencies, 17.8% to equity, 15.8% to fixed income and 36.1 to "stocks and industries" which I presume are narrower, more idiosyncratic bets in the equity market.

The QIS info pages say the fund allocates to 10-20 quantitative investment strategies in equities, interest rates, commodities, currencies and credit. It's an ETF so the positions are published, here is a partial screen grab.


Again, that is a partial list only. The fund primarily accesses QIS in the manner described in the Bloomberg article with total return swaps. There is a debit put spread on the S&P 500 which all by itself is a bearish position but I can't find anything to indicate what the current strategies are. So if there is better transparency for QIS, it's not that easy to find on the website.

Is there any reason to consider either of these funds or any others that might track one version of QIS or another? If there is a reason to buy QRPIX, I think it would be because an investor believed it to be a better mousetrap. It's managed futures-ish (with a couple of other things thrown in too) in terms of what it has done over the last six years. 

The reason to consider QIS is a little different. Look at this backtest.


Again, it is insanely short because of how new QIS is. Client/personal holding PPFIX sells index puts that are very far out of the money as one type absolute return stream, floating rate debt is a different type of absolute return stream so it relies on different things than PPFIX and has different risks than PPFIX. Arbitrage, not in the back test, would be a third type of absolute return stream. QIS could potentially be a fourth type of absolute return stream. It would need to prove that it can actually deliver an absolute return stream and if I was going to consider QIS, I'd want to make sure it doesn't over lap with arbitrage strategies. 

The word arbitrage is not in the prospectus so it potentially is a fourth kind of absolute return stream. The appeal then would be a new tool for diversifying your diversifiers. We can see in a year or two if it starts to prove itself out as I am describing which is based on the expectation I believe is being set by the fund but of course I could be wrong or the fund might not be able to execute as hoped for if my impression about the expectation is correct. 

I'll just close out on the idea of giving something a year or two, or longer, to prove out. It is important to really play the long game with these sorts of things. For as much as I talk about managed futures and as happy as I was with the exposure during the financial crisis, I stayed away from the strategy for 8 or 9 years until buying Standpoint Multi-Asset (BLNDX) in early 2020. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Tuesday, June 11, 2024

Diversification Is Alive & Well!

Yesterday we asked if diversification was dead. It is of course not dead but bonds became a far less effective diversifier years ago, long before 2022 when interest rates started going up. The reason I say that is with rates on their way to zero, the risk to holding longer duration bonds went up. The risk was there for years, 2022 when when there was a consequence to investors who took that risk. 

Avoiding long duration bonds was a big theme to my writing (and portfolio construction) for a long time, still is, but then the thought evolved to where I started saying that long duration fixed income has a source of unreliable volatility that makes it very difficult to model it in to a portfolio with any confidence. 

Finomial drew a similar conclusion about fixed income awhile back and posted this paper where they subbed in 40% into managed futures. I would say that is a very big bet but the math in their backtest supports it. 


Obviously, their study is compelling but it is not clear to me that the intention is to suggest anyone actually put 40% into managed futures. I would argue that the 40, or whatever percentage not in equities, be spit amongst various attributes in order to diversify your diversifiers or as we talked about the other day, to add differentiated return streams. 

I try to articulate these by saying what they do, it makes it easier when anyone asks. So, client/personal holding BTAL is very reliably, in my opinion, negatively correlated to stocks. Managed futures although is negatively correlated, is more crisis alpha to me that can go up in any environment. Things like merger arbitrage are horizontal lines that tilt upwards almost all the time so they do relatively well when stocks are lagging and do relatively poorly when stocks are doing well. There are alts, like global macro, which tend to have no correlation to equities. At times they will do better and be capable of going up a lot but sometimes not. Lastly, shorter term income sectors like T-bills or floating rate that don't really take meaningful interest rate risk but now have higher yields. 

And finally because I think it is related, this ridiculously short chart, because that's all we have for now, is interesting. Those are three of the four ReturnStacked funds compared to the Vanguard S&P 500 ETF. It's only two weeks which is ridiculously short (repeated for emphasis) but these all seem to be doing different things. 


I don't really ever see myself using their funds but that doesn't mean we can't learn some things about diversification. If these still look totally different a year from now, it would be productive to try to understand these dynamics better. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Monday, June 10, 2024

Is Diversification Dead?

The title of today's post is essentially the question asked in a Bloomberg Article (syndicated at Yahoo). The TLDR is that broad diversification has lagged behind simple market cap weighting for the last 15 years. I am guessing they chose that timeframe to coincide with the March 2009 bottom. 

We've talked just a couple of times about the market becoming increasingly concentrated which just in terms of math means that a diversified strategy will lag for as long as the big names do well. According to the article, the only "asset allocation" fund to outperform the S&P 500 over the last 15 years has been the PIMCO StocksPLUS Long Duration Fund (PSLDX) which ironically enough is a leveraged fund tracking 100% each to stocks and long term bonds. The concentration issue could continue to accelerate from here with Evercore saying they can see Nvidia (NVDA) growing to 15% of the S&P 500 from its current six-ish.

This sort of top heavy market is a negative for the market. The largest stocks need to continue to do a lot of heavy lift for the market to have its best chance of continuing higher. That does not mean stocks must go lower and of course it is possible for the index to lift without the big three, just that it makes it more difficult. There are always reasons for markets to go up and always risk factors, this is merely a risk factor. 

Despite outperforming for 15 years, PSLDX was down 43% in 2022 which speaks to what diversification is about. Outperformed long term but down a sickening 43% and still down about 25% from its late 2021 highwater mark. In thinking about diversification, what problem are you trying to solve? Or maybe a better way to put it is, what outcome are you trying to avoid while at the same time, what are you trying to achieve?

One headwind to how investors think about diversification is that it is easy and common to forget what large declines feel like after a few months or a couple of years of strong market performance like we're sitting on right now. This is the point in the cycle where the sentiment of "should I put it all in the S&P 500 and forget about it?" happens. The answer for most investors is no. The time to ask that question is after a large decline like Q3, 2022 and the answer for most investors would still be no. 

Going 100% S&P 500 can absolutely get the job done but every now and then the declines will be brutal which is why diversification exists. How many articles have you read about bonds being a good ballast for equity volatility? The love the word ballast. 

Diversification has multiple reasons to exist. First is to help cushion the blow of large declines. Bonds did that for 40 years as interest rates went from mid-teens to just north of zero. In 2022 they didn't work. This might be an example for Karl Popper; all the positives in the world can't prove a theory but it only takes one negative to disprove a theory. 2022 was the negative to disprove that bonds with duration effectively diversify against equity volatility. 

Another important reason for diversification is to avoid an adverse sequence of returns disrupting some sort of near term life event, typically we talk about retiring in this context. Long duration fixed income has always had equity beta, it just so happens that 2022 is when it worked against investors. I looked at the Vanguard Target Retirement 2025 (VTTVX) and the Vanguard Target Retirement 2030 (VTHRX). In 2022 they were down 15.55% and 16.27% respectively, just slightly ahead of Vanguard Balanced Index (VBAIX) which was down 16.87%. I've been bagging on target date funds since they first came out with 2022 being the latest example of why I think they stink. They can get the job done if that is all someone has access to in their 401k but they need to figure something out as they get close to retiring because they are not protected against sequence of return risk.

Back to the questions above, what are you trying to achieve, what outcomes do you want. The point of diversification is to (hopefully) be less volatile than the broad market to minimize the odds of succumbing to emotion and panic selling along with getting a long term rate of growth adequate enough to ensure you have have enough when you need it and stay at least a little ahead of price inflation. All the better if all that can be done without constantly worrying about the ups and downs of markets.

Quick pivot to close out, again invoking Karl Popper. For many years I talked about zero weighting to a sector as being a big bet even if unintentionally. I've been effectively zero weight energy in terms of big oil for quite a while now. Here's an interesting chart comparing the S&P 500 and the Pro-Shares S&P 500 ex-Energy (SPXE).


ETF.com has the energy sector currently at 3.1% of the S&P 500. Back before the financial crisis it was closer to 6% and 40 years ago it was 30% believe it or not. In the period available to study SPXE, there has been no difference in  returns, volatility or portfolio stats. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.
Sunday, June 09, 2024

Closed End Funds Ain't Easy

Barron's had a quick writeup on tactical funds that can switch between equity and fixed income exposure, either making big changes to their allocations or small tweaks to their allocations. The implication from the article was that the turnover in these is very high. The reason for the article is that "some of these funds are worthy diversifiers for a traditional fixed allocation portfolio."

There were three that stood out as being interesting for blogging purposes because they invest in closed end funds.  

  • Modern Capital Tactical Income (MCTOX)
  • Matisse Discounted Closed End Fund Strategy (MCDEX)
  • Saba Closed End Funds (CEFS)

With the old style mutual funds, I just used the symbols from the article, you'd probably use different share class symbols if you actually intended to buy either of them. Ask your brokerage firm what the correct symbol for you would be. While I am assuming no one will want any of these funds, in general, asking the brokerage for the correct symbol is a good idea. 

All three are more volatile than the Vanguard Balanced Index Fund (VBAIX) which is a proxy for a 60/40 portfolio. MCTOX just started trading in 2021. It is a very small fund but it has a 5 star rating probably because it was up in 2022. It has a much better CAGR than the other two in the short period available because it was up about 13% in 2022 versus mid-single digit declines for the other two. 

I couldn't get a great sense of the investment process from the website but it talked about mispriced securities, value and event driven as contributors to the process. I'm sure talking to them would yield a better sense of what they actually do but we do know, they made at least one very good call in 2022. The process for MCDEX is laid out more plainly. First in screens for funds trading at a discount, then a second step assessing many qualitative factors and then blending CEFs together such that there is at least a little contrarianism embedded. The SABA fund buys funds trading at a discount and hedges interest rate risk. 

Statistically, MCTOX looks a little better but the track is short. Generally the portfolio stats and standard deviation are not great for these and the correlation is pretty high. The great year for MCTOX appears to distort it's track record. If it ever repeats that type of year, that would get my attention but given the vagaries of this space, intriguing as I've found it to be over the last 30 years and counting, it is difficult to make a meaningful allocation.

Closed end funds are more complicated than they seem. In addition to understanding the underlying market a fund is tracking, there needs to be an analysis of the premium or discount to NAV and what might come next for the premium or discount. Did I say analysis? I meant guesswork.  

Blogger Nomadic Samuel Tweeted an interview with Kevin Maki who allocates 50% to quality stocks and 50% to "momentum and trend." I wanted to play around with the momentum and trend idea as follows.


Portfolio 3 is VBAIX. Unlike trying to figure out MCTOX, the back test is decently long to observe various market environments and enough years where the outperformance of 2022 doesn't skew the entire study. Additionally, if you believe in managed futures as a diversifier then you probably think the 2022 result is repeatable the next time there is a big decline, I certainly believe that to be the case.


For what it's worth, QUAL did a little worse than market cap weighted S&P 500 in 2022 and MTUM was essentially right in line, so the 2022 outperformance was attributable to managed futures.


The bigger takeaway for me is that this sort of blend is yet another example where effective portfolio diversification can be had with out adding the dysfunction of longer duration fixed income. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Friday, June 07, 2024

The Wrong Way To Look At Social Security

A bunch of quick hits from this weekends Barron's as the articles come out today.

For all the worry about retirement readiness, Barrons found a survey where retirees say they are doing just fine. That's great but not really what the potential crisis is about. If there is a problem, it is with people still working who are collectively very undersaved for their retirement. 

It was an odd framing but not the reason to mention the article. There were a couple of comments, always read the comments, that said in effect, how much trouble people are in if Social Security is their primary source of income once they retire. A similar personal anecdote where someone was conversationally dismissive of the income from our Airbnb rental. We currently average a little over double our mortgage payment for the rental and the cabin will be paid off when I am 66. 

My reaction to both sentiments is the same. How great would it be for Social Security to cover a huge chunk of known expenses? How great would it be for a modest income stream (the rental is unambiguously cash flow positive but the dollars involved are not huge) to cover a meaningful chunk of known expenses? Modest income stream could apply to many different things, in this example it is a rental. 

There is a balance to be struck between living in the moment and doing favors, financial and otherwise, for your future self but being able to easily cover your retirement nut is a reward for many years of living below your means. How much will your Social Security be even if you haircut it by 20%? I repeat, how great would it be if your Social Security covered half or maybe more? How much easier would retirement be if that was the case? How much easier would it be if a $20,000 or $30,000 income stream was enough to have a meaningful impact on covering your expenses? 

The second article to look at was about investing in sports collectibles which is coincidental to yesterday's joke about a Rickey Henderson rookie card. There was one traditional advisor quoted who also advises on collectibles. He said if you have $ 1million to allocate to collectibles look for game worn jerseys of the most elite player you can afford (I am not going to use the term GOAT), if your budget is $100,000 look for second tier all timers like "Ted Williams or Stan Musial," for $10,000 buy a card of a first tier all-timer and if you have $1000, just keep your money. He added, or just collect what you like. 

I sort of collect baseball and basketball cards. It's very few actual cards issued by Topps or other card companies, I have more custom or art cards which are very cheap. There's quite few people who make these up. They are the same quality, they look great and are very cheap (repeated for emphasis), like $1-$10. A while back I mentioned having a 1970/71 Bobby Orr card that I bought for $20 that was worth $300 or so when I wrote about it so maybe it went up a little more. I made some sort of joke that even if I knew it would go up that much, it's not like I could buy a few hundred of them for the gain.

I might be sitting on a more meaningful gain on something else though. I stumbled into Daniel Jacob Horine early on in the pandemic on Twitter where his handle is Pop Fly Shop. He had started making mashups of baseball and comic books as small art pieces. I found him early but just stuck to buying what I liked for $35 back then including the pictured Nolan Ryan. A few months later he was featured on the MLB Network twice and his popularity blew up going from selling tens of prints each week to hundreds each week. The Ryan is one of only 88. A couple of years ago, a couple of the Ryans sold in the $2500-$3000 range. This past week, someone was trying to sell one for $6000. If the market really is there, then I will try to sell mine. If the market is not there, I'm happy to keep it.


The print is still in the wrapper it came in, inside the frame. The cards in there with it are examples of custom cards. The reason to tell this story is to reiterate from previous posts how unlikely it will be to actually make money that is meaningful unless you are at the Christies Auction level of engagement. I had no inkling the Pop Fly art would have any value otherwise I would have bought all the early ones. I suppose if someone made it their fulltime job, they might be able to have a meaningful impact on their finances assuming the more you put into something the more you get out of it holds true in collecting. I don't know if it does but if nothing else they are fun little pieces of art to have.  

The next article took an uncharacteristically (for most mainstream media) skeptical look at annuities. The short version is that quite a few annuity providers have large allocations to private placement loans which increase the risk of problems in the space arising. Odd that the term "private credit" was not used. If you do a little digging you will find a lot of current content about the threat to markets posed by private credit.

I've long been anti-annuity. I believe part of my bias stems from my mother having annuity, through my older brother, that failed. She got something like 30 or 33 cents on the dollar eventually. I don't know the details beyond that but interestingly, the Barron's article talks about a large failure at Executive Life in 1991. I don't know if that is the one that my mom got caught up in but it made for interesting reading. 

To be clear, while I do have a bias against annuities as they are commonly structured, I still believe the way in which assets can be annuitized is an important space to follow. I've mentioned the Stone Ridge mutual funds that transition into a longevity pool and Blackrock is sniffing around the space with something vaguely similar. These have the potential to be helpful in a way that I'd say would be a huge improvement over traditional annuities. 

Bill Ackman is listing a new closed end fund that will apparently "overlap" to some degree with his closed end fund that trades in Europe. The US symbol will be PSUS and the OTC symbol for the one in Europe is PSHZF. Barron's has PSHZF trading at a 25% discount to NAV. The way closed end funds typically get listed in the US is there is a selling concession (a commission of sorts) embedded in the offering price so they are issued at a premium to NAV which quickly corrects but maybe PSUS will be different.


PSUS will have a 2% fee but as Barron's notes, his holding can be replicated up to a point for less. PSHZF has done quite well lately but the fee and structure is a little disappointing.

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Thursday, June 06, 2024

Allocating To Game Stop Gift Cards?

Several quick hits today.

GraniteShares has filed for a suite of what it will call YieldBoost ETFs that will sell put options on levered index and single stock ETFs ranging from 1.5x-3x levered funds. Like a lot of the "derivative income funds," the yields will be sky high. The market won't go against the strategy too often but occasionally, when there are large declines, the risk to these getting torched would be enormous. That's probably a better description for the YieldBoost funds tracking indexes, with single stocks of course the market could turn on them at anytime. 

Like quite a few of the newer derivative income funds, it will be a tall order for the market price to keep up with the dividends which is why I've said that if you need to own any of these, you should reinvest a meaningful portion of the dividend. Not keeping up with the dividend is not the market going against the strategy, more like the strategy going against holders who spend the entire dividend. 

JEPY sells puts, hasn't been around very long and almost looks negatively correlated to the S&P 500.


Since it came out last September, it has paid $6 in dividends. Add that back into the $20/share it started at and the fund is up about 10% on a total return basis. Still far behind the index it tracks but a good example of why reinvesting the dividend should be considered. 

The YieldMax Microstrategy ETF (MSTY) announced its next dividend this morning. MSTY is trading at $31 and change after going ex-div for $3.03 which annualizes out to 106% according to the press release. If Bitcoin doubles from here over the next year then MSTY could very well keep up with that payout but up or down 10% on Bitcoin and I don't see how it could. 


I don't know if the current batch of derivative income funds are the final solution or not but I think at a higher level these funds are part of a movement that is trying to figure out how to harness volatility as a strategy in a retail accessible fund to improve nominal returns or risk adjusted returns. 

A month and a half ago I wrote about the ABR 75/25 Volatility Fund (VOLSX). The title of that post was What The Hell Is This Fund Trying To Do? Crisis alpha is mentioned in the literature but unfortunately the fund lagged far behind the S&P 500 and the Vanguard Balanced Index Fund (VBAIX) in 2022. The fund builds a diverse portfolio of stocks and fixed income and layers long and short volatility in there to seek its objective. Maybe it has a great year coming the next time there is a decline but I don't know that there is any reasonable basis to expect that to happen. The reason to mention VOLSX is that figuring out how to use volatility as a strategy in a fund is not easy.

Blogger Nomadic Samuel posted an interview with Jay Kaeppel who has an interesting spin on asset allocation with what he describes as 30/30/30/10. The first 30% is in plain vanilla stocks, bonds or maybe commodities although he prefers dividend paying value stocks, the second 30 is trend following, then 30% in "objective strategies or systems" and the last 10% in "whatever." There's more to it than that so read the interview if you're curious but I wanted to build an overly simplistic version of this idea.


I chose client holding ROBO as the whatever because I've held it for ages, it has at times outperformed, at times it has lagged but I am not cherry picking the top performing thing I have to distort the results. The other holdings are in the narrow universe of things I use for blogging purposes not what I own for clients. 


I am surprised how closely it tracks to VBAIX. It outperforms by a little, is a little less volatile but outperformed meaningfully in 2022. In the backtest it was down 3.65% in 2015, that worst year was 2018 and in 2022 it was only down 2.72%. It outperformed VBAIX in 5 of ten years including this year so far so not a world beater but clearly a decent performer. Given that much of the period studied was kind of a dark ages for managed futures, it might be able to do a little better going forward especially if interest rates stay off zero. 

And finally a little fun with a crypto called Mother Iggy.


The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Wednesday, June 05, 2024

Blending Tail Risk and Asymmetry

Let's do some crazy stuff with this post....crazy.

I've been thinking about the Alpha Architect Tail Risk ETF (CAOS) that we wrote about the other day. As I mentioned, I am not sure whether it would actually go up if there was a serious, fast-ish decline. It very well could work but it hasn't been tested yet. I do believe it can function as a short term cash proxy if nothing else that might go up like a tail risk strategy when the next meaningful decline happens. I don't think the risk to holders from the option strategy would be ruinous. 

For purposes of this post we'll give it the benefit of the doubt, cash proxy most of the time and tail protection when the market drops a lot. The cash proxy, might be tail risk too reminded me of Nassim Taleb. He is some sort of advisor to Universa Investments which specializes in tail risk protection. He's written and talked about tail risk frequently. It's an interesting idea and if CAOS turns out to not be the answer, maybe something else in the future will be. 

Another concept that Taleb has written many times about is asymmetry. Starting back in 2007 or 2008 I wrote about his barbell portfolio idea that goes very high risk with 10% of the portfolio in search of asymmetric returns and then very conservative with the other 90%. The returns generated from the 10% could almost be enough for the entire portfolio. Think in terms of putting 10% into a stock that doubles, the stock would be up 100% which would be 10% for the overall portfolio, plus whatever yield the conservative 90% could bring in. 

Here's an example of the effect.


Of course it is backwards looking and cherry picked. The narrative is not "all you need to do is pick a stock that doubles." There are lessons here though for how to allocate to higher risk, higher volatility which is not so far removed from reality. Chances are if you go to the sector level in your portfolio construction, you're not expecting huge gains from the staples sector but it is reasonable to expect the best chance for adding performance to your portfolio will come from tech, discretionary or maybe a couple of others. Things like staples and utilities tend to be lower returning, higher yielding. 

So back to Taleb's ideas of tail risk and asymmetry. We'll use CAOS for tail risk and what has more asymmetric opportunity than Bitcoin? Maybe Bitcoin goes to zero or maybe it goes to a bazillion.  CAOS only has about a year of track record but that's ok, it's just a blog post. 


The numbers for Portfolios 1 and 3 add up to 105% because I am replicating 5% into a 2x bitcoin fund. There's at least one, the symbol is BITX, it is just a few months old so we can't really backtest it but it is form of capital efficiency that someone could implement if they wanted.

Portfolio 1 is full blown Taleb-concept with 95% in tail risk and 5% in 2x bitcoin. Portfolio 3 is more of a diversified portfolio. I believe uranium miners to be somewhat asymmetric. The time period is too short to be useful in any way but it is interesting. 1 and 3 dramatically outperformed with much lower standard deviation and the Sharpe and Sortino are meaningfully higher than 60/40.

Since CAOS hasn't had a real test of going up in a serious decline, if we replace it with more T-bills to get a longer backtest, the results are similar.


It only goes back to 2018 because in 2017, Bitcoin went up an amount that may not be repeatable. Portfolios 1 and 3 both concentrate the risk into narrow slices of the portfolio.

I've told the story 100 times about my first exposure to what is now called capital efficiency. When I worked at Fisher Investments 22 years ago, there were a couple of guys who were fascinated by the idea that for a stretch, 2% allocated to short Nikkei futures equaled the return of the S&P 500. I don't know if they were right but it is a great example of the barbelling that Taleb used to talk about. market like returns with very little capital at risk. 

The blending of tail risk and asymmetry also carries on an almost 20 year conversation about my very obvious and un-unique observation that the fund space would evolve to offer increasingly sophisticated strategies and tools to retail-sized investors. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Tuesday, June 04, 2024

Differentiated Return Streams

We spend a lot of time here dissecting alternatives in pursuit of refining the portfolio to being more resilient in the face of serious declines and trying to improve risk adjusted results. One high level aspect of this process is trying to understand what to expect from a particular fund. For some funds it is easy to figure out what it is trying to do, regardless of whether it succeeds, you can figure out what the goal is.

Some funds are more difficult to figure out. One that puzzled me for its short time was the Noble Absolute Return Fund (NOPE). Here's a chart from a blog post that mentioned it back on April 5.


Absolute return typically implies some sort of low vol outcome where it will go up a lot less when stocks are rally hard and will be flat or maybe up a little when stocks have a big drop. It came out like a fire cracker showing enormous swings in both directions. Then it appears something in the strategy changed, it traded with a slight downward tilt before closing. There was no way to model something like that into a portfolio. Despite the volatility, it was not an asymmetric opportunity like Bitcoin or maybe uranium. I tried but could never figure it out. 

Contrast that with something like merger arbitrage or convertible arbitrage. Those two are examples of what I call horizontal lines that tilt upwards slightly. I believe them to be very reliable in this regard. There are others we've looked at that should have a negative correlation to equities that also deliver on that expectation. 

Not only am I trying to understand the expectation that I think is being set, I think there needs to be some reasonable basis to expect it can meet that expectation. We've looked at several funds from Simplify where the expectation seemed easy to understand but just didn't execute including its failed tail risk fund and the Simplify US Equity PLUS Downside Convexity ETF (SPD) which owns the S&P 500 with a put option overlay for protection. In 2022 SPD was down 25.96% versus 18.19% for the Vanguard S&P 500 ETF (VOO). 

All of that brings us to the Unlimited HFND Multi-Strategy Return Tracker (HFND). It bundles long/short equity, global macro, event driven, fixed income arbitrage, emerging markets and managed futures into a replication product. It's managed by Bob Elliott who having heard him speak many times, I believe he knows his stuff. 

Per an email from Unlimited the fund is trying to offer "core, liquid, uncorrelated ballast within overall asset allocation." It's only been trading since late 2022. 


The expectation is easy to understand but should we have basis to expect it can do what it is trying to do? So far, the answer is no but there hasn't really been a test yet. The fund is actively managed so it could look much different when the next big decline comes and maybe it will do fantastically well but for now there is no way to know. It has a 0.87 correlation to VOO and a 0.89 correlation to VBAIX. They would probably argue that since inception, it has made sense to have a high correlation to VOO and VBAIX and they'd be right. Some strategies it clicks right away that it will work as advertised with client/personal holdings BTAL and BLNDX being examples but HFND needs to show it can differentiate. 

Another example of an interesting fund still needs to prove it works is the Alpha Architect Tail Risk ETF (CAOS). Tail risk has proven difficult to package into a fund. I mentioned the Simplify fund that failed. The Cambria Tail Risk fund lost a lot of ground from holding longer dated treasuries and the erosion of the puts the fund owns. CAOS has it's cash in very short term instruments to hopefully avoid interest rate risk and instead of simple put exposure it combines puts and calls in such a way that so far has been additive versus T-bills since its inception. CAOS did have noticeable dip in April of this year though. 


A slice in CAOS certainly has not hurt returns but during the shallow decline you see on the back test from August 2023-November 2023, CAOS was down a few basis points. Obviously it didn't hurt returns or make that dip worse but it did not go up as 60/40 dropped about 5%. Where it is a tail risk strategy, it might only "work" when there are big declines as opposed to gradual dips. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Monday, June 03, 2024

Making It Work Because You Have To

Yahoo had an interview with Ed Slott who is a preeminent expert on Roth conversions, or at least a very well know proponent of them. This has been his thing for a long time. Part of the equation is that he is convinced that tax rates have to go up to pay for out debt and so converting to a Roth now before tax rates do go up will result in people ending up with more after tax dollars versus just going the RMD route at what is now 73 on its way to 75. I'm paraphrasing Slott. 

I haven't seen too many scenarios where Roth conversions were optimal as most people don't earn more after they retire. Do the math on your particulars like what your various sources of earned income will likely be, how much your RMDs will likely be and so on. 

One no brainer scenario for me for Roth conversions is one we talk about frequently where someone's hand is forced into retirement either from downsizing or health reasons or even just retiring early with no earned income. Someone in their 50's or 60's living on (qualified) dividends and long term capital gains could convert some of their dollars tax free pointing toward the standard deduction and a few more dollars at a very low effective tax rate. At $80,000 of earned income solely from a Roth conversion, Nerd Wallet has the taxable income at $52,300 with Federal tax owed at $5836. If anyone is in this situation and can pull this off, big if, then yes, it makes a lot of sense. Imagine 10-15 years of this before taking Social Security, how much of your traditional IRA would that clear out? Work with your accountant though. 

With more normal scenarios, really crunch the numbers with your accountant. 

Among the comments which mostly accused Slott of pedaling fear in order to sell a book was this interesting comment.


Always read the comments. This point is more interesting than the conversion idea. I won't get into this person's qualitative judgment about how much someone else needs but how much do you think you need? If you are 50 or 55 or 60, are you able to assess how likely you are to end up with what you think you need? $500,000 is fine sum to accumulate but someone who thinks they need $1.3 million but ends up with $500,000 is going to have to make some very difficult decisions and concessions. 

Some goal, your number, is fine to shoot for but whatever you end up with is your reality. $1.3 million as a goal means nothing to the person who ends up with $500,000. $500,000 becomes the reality they have to adapt to. 

If you have a goal, what is it based on? I have no goal, no number in the normal context. We live a $4500/mo lifestyle in terms of fixed expenses. Non monthly expenses like property tax and property/car insurance has gone up lately, maybe this year it's about $13,000. Then maybe a few thousand a year for unbudgetable one-offs like vehicle repair and veterinary bills. For us, maybe that's $6600/mo or rounded up to $80,000/yr. We do fun things, but that is discretionary of course and we could reduce or cut if we had to. We "spend" a lot on contributing to my 401k, HSA and so on but that is also discretionary. If my income dropped dramatically, we'd just not contribute or contribute less. 

When I am 65 I will be on Medicare but still working so Part B might be expensive so maybe our health insurance in today's dollars would drop by $400, it will be 6 years after that before my wife gets Medicare. One month after I turn 66 the mortgage on our rental will be paid off which cuts another $1500/mo off our nut. 

Go through this sort of bottom up process with your numbers. How much will you actually need? If you've been living below your means then what you need should be less than you've been making. We very fortunately are doing better than $80,000 and in just seven years, the number will start to go down in today's dollars which makes this self assessment stress free.

What can you do now to lower your number if going through this exercise causes stress or anxiety? 

Back to the reality of income sources. What will your Social Security be? They want you to know. What will it be if they haircut by 20%? If you believe it will be cut then go with that number. This paper reiterates a point we've made that benefit cuts will start with Millennials, not Gen-X but even if you don't believe yours will be cut, maybe go with the reduced number anyway to be conservative.

How much are you likely to end up with in your retirement accounts? If you're 60, want to retire at 66 and have $800,000, you're not likely to end up with $3 million six years from now. This example putting in $15,000 into a 60/40 fund compounding at 9% just like VBAIX did for the last 6 years would wind up with $1.4 million six years from now according to Portfoliovisualizer. That's not infallible for course but it's better than nothing. Portfoliovisualizer has a free tier for you to do this work for your numbers. 

How much can you take from your portfolio? The standard default is 4%. Once you fully understand where 4% comes from, the odds that 5% is safe are very high. Every advisor has a couple of clients who withdraw way above 4-5%, I certainly do but the market of the last 15 years or so has bailed those people out. It may be problematic to expect that in the future. 

What does your SS plus 4-5% of your savings add up to? Is it enough in terms of dollars and cents, what about in terms of emotional comfort? Where do you stand? Does it look like you can be resilient in case something expensive unexpectedly comes along? What something expensive that maybe is expensive like replacing a car at some point? 

If you are short or otherwise not comfortable enough, what are you going to do? Will you keep working? Can you cut your expenses? Can you monetize something? Not too many people have pensions these days, do you have a source of "passive" income like from a property rental?

There's a lot of open ended questions here of course and there will be contingencies and changes that cannot be planned for, but it's just a little work to understand your numbers as you expect them to be and then be able to adapt if you do have to make changes. 

Ultimately, whatever number you end up with will be your reality and you will make it work because you have to. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Sunday, June 02, 2024

The Replicators Are Coming!

Alpha Simplex wrote a short but wide ranging paper that covered the history of managed futures as a strategy, the history of that strategy working its way to retail accessible funds and the possible benefits managed futures in ETFs of which there are now quite a few. The firm has been running the Alpha Simplex Managed Futures Strategy Fund (ASFYX) since 2010. The paper seems to support the very new Alpha Simplex Managed Futures ETF (ASMF) which started trading in mid-May.

The difference between the two is that ASFYX runs a managed futures strategy with their own process that as of March 28 had 102 positions (45 long, 57 short). ASFYX also has a small percentage of its assets tracking a faster signal than the normal 200 day/10 months that most managed futures strategies follow. The new ETF is a replication of many managers different managers but only allocates into 20 markets. The complexity of the strategy lends itself better to mutual funds for reasons the paper gets into and replication, for now anyway, is easier for the ETF wrapper to participate in the space.

When I've said in past posts that not everything lends itself to the ETF wrapper, managed futures strategies was one example I had in mind. That doesn't mean strategy must be better than replication. Replication certainly is simpler. Andrew Beer who runs the iMGP DBi Managed Futures Strategy ETF (DBMF), a replication strategy, said in that webinar I mentioned the other day, that DBMF can replicate with just 10 different markets to get about 90% of the effect. Replication also avoids idiosyncratic (manager) risk. Yes, DBMF having the word strategy in the name is confusing but logically, there will be times where replication will outperform and times where it lags so saying one is better isn't the way to frame it. 

I hold ASFYX for clients and personally on the differentiation I mentioned above regarding the faster signal.

Here's an article I wrote for theStreet.com in March, 2008 about the Rydex (now Guggenheim) Managed Futures (RYMFX). I've mentioned quite a few times that I think it was the first mutual fund in the space and the Alpha Simplex paper seems to be confirming that without naming the fund. That was the second article I wrote about RYMFX but the first one appears to not be on the internet anymore. In the article I said I had owned it for about a year so I apparently bought it when it was brand new. 

Now, 17 years later, I don't recall the process that led me to the fund or the research I did to actually buy it but my assessment of its strengths and weaknesses back then was on point. I'd like to think I understand it much better than I did back then but it is interesting to see what parts of my investment process have stayed the same which is wanting to know what expectations a strategy is setting, knowing the drawbacks and sizing appropriately. Editorial note, how in the hell have 17 years gone by? LOL

The paper quickly mentioned carry and global macro as other examples of trend. Managed futures falls under the header of trend but the two terms are often used interchangeably. We've talked quite a bit about carry lately as I try to figure out what I think. For now, I am skeptical of the various that goes long commodities in backwardation and short the commodities that are in contango. I can believe that the strategy compounds positively but allocating based on trend (regular managed futures) seems more reliable to me than allocating based on term structure. 

Some people invest on fundamentals and some invest on technicals but this manifestation of carry doesn't seem to do either. I will continue to try to learn more. The type of carry that goes long higher yielding currencies and short lower yielding currencies can be found as part of many funds that include the terms market neutral, absolute return and global macro in their names and that seems a little more reliable than the other carry because there is some fundamental element in there to account for at least some of the return. 

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Saturday, June 01, 2024

Don't Get Inflation Wrong

Barron's had a short article about replacing 60/40 with 60/30/10 due to inflation. I'm always going to want to dig into an article like that. In this case the the idea was 60% in equities, 30% in bonds and 10% in TIPS. TIPS or treasury inflation protected securities are conceptually straight forward. In addition to an interest payment, the price gets adjusted higher at the rate of reported headline inflation. So maybe you buy a TIPS at 100 cents on the dollar but after holding it for some numbers of years you might get 120 cents on the dollar back at maturity. The 20 cents would be the inflation protection. One complicating factor is that tax is owed annually on the amount of the par value adjustment so qualified accounts might be better for individual TIPS.

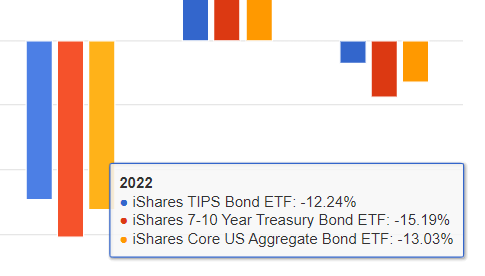
The article quotes an analyst from Alliance Bernstein as saying "if there are any unexpected inflation hikes, you are immunized from those spikes." That sounds good of course but in reality, being immunized isn't exactly how it played out in 2022. Inflation did spike but so did interest rates and investors learned that TIPS are interest rate sensitive just like bonds. 


Obviously, TIP did a little better in 2022 but I would bet that someone holding TIP would have hoped for better than 79 basis points versus AGG. Short dated TIPS ETFs did much better, dropping mid-single digits but that still might have been a mild disappointment. An investor might think, inflation spiked, well that's not good but at least I have some TIPS and then they see their TIPS exposure is down too. 

That's what makes the Barron's article a little of a head scratcher. So 10% in TIPS to protect against inflation?


Yes, the short dated TIPS exposure helped incrementally versus the other two but it was very slight. The worst year for all three was of course 2022. If someone had made this suggestion ten years ago, ok, yeah, if inflation comes back a decent allocation to TIPS might help. But now, inflation did come back and a decent allocation to TIPS did almost nothing. From here, going forward if inflation stays where it is and interest rates stay about the same then yes you might a "real yield" kicker to help but if rates spike to a higher level, TIPS would again go down.

I think putting the 10% into broad commodities or managed futures Would be a more effective hedge against inflation than TIPS. It might make sense to do other things in addition to 10% in commodities or managed futures for more robust protection against inflation but for now we'll stick with the 10% highlighted in Barron's.


In this study, broad commodities did better than gold in 2022 but on the next go around gold might do better. Broad commodities and managed futures were both up a lot in 2022, gold was flat, long dated TIPS were down low double digits and short dated TIPS were down mid single digits. 

The correlation matrix helps shed some light.


Having negatively correlated assets was more reliable than TIPS exposure and for my money, that will continue into the future.

The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. They are not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation.

Did An Autocallable ETF Just Malfunction?

We have called out the ProShares S&P 500 Autocallable Income ETF (ACSP) as being more volatile than many of the other funds in the space...